Global Smartphone Shipments Share - Last Eight Years of Winners & Losers
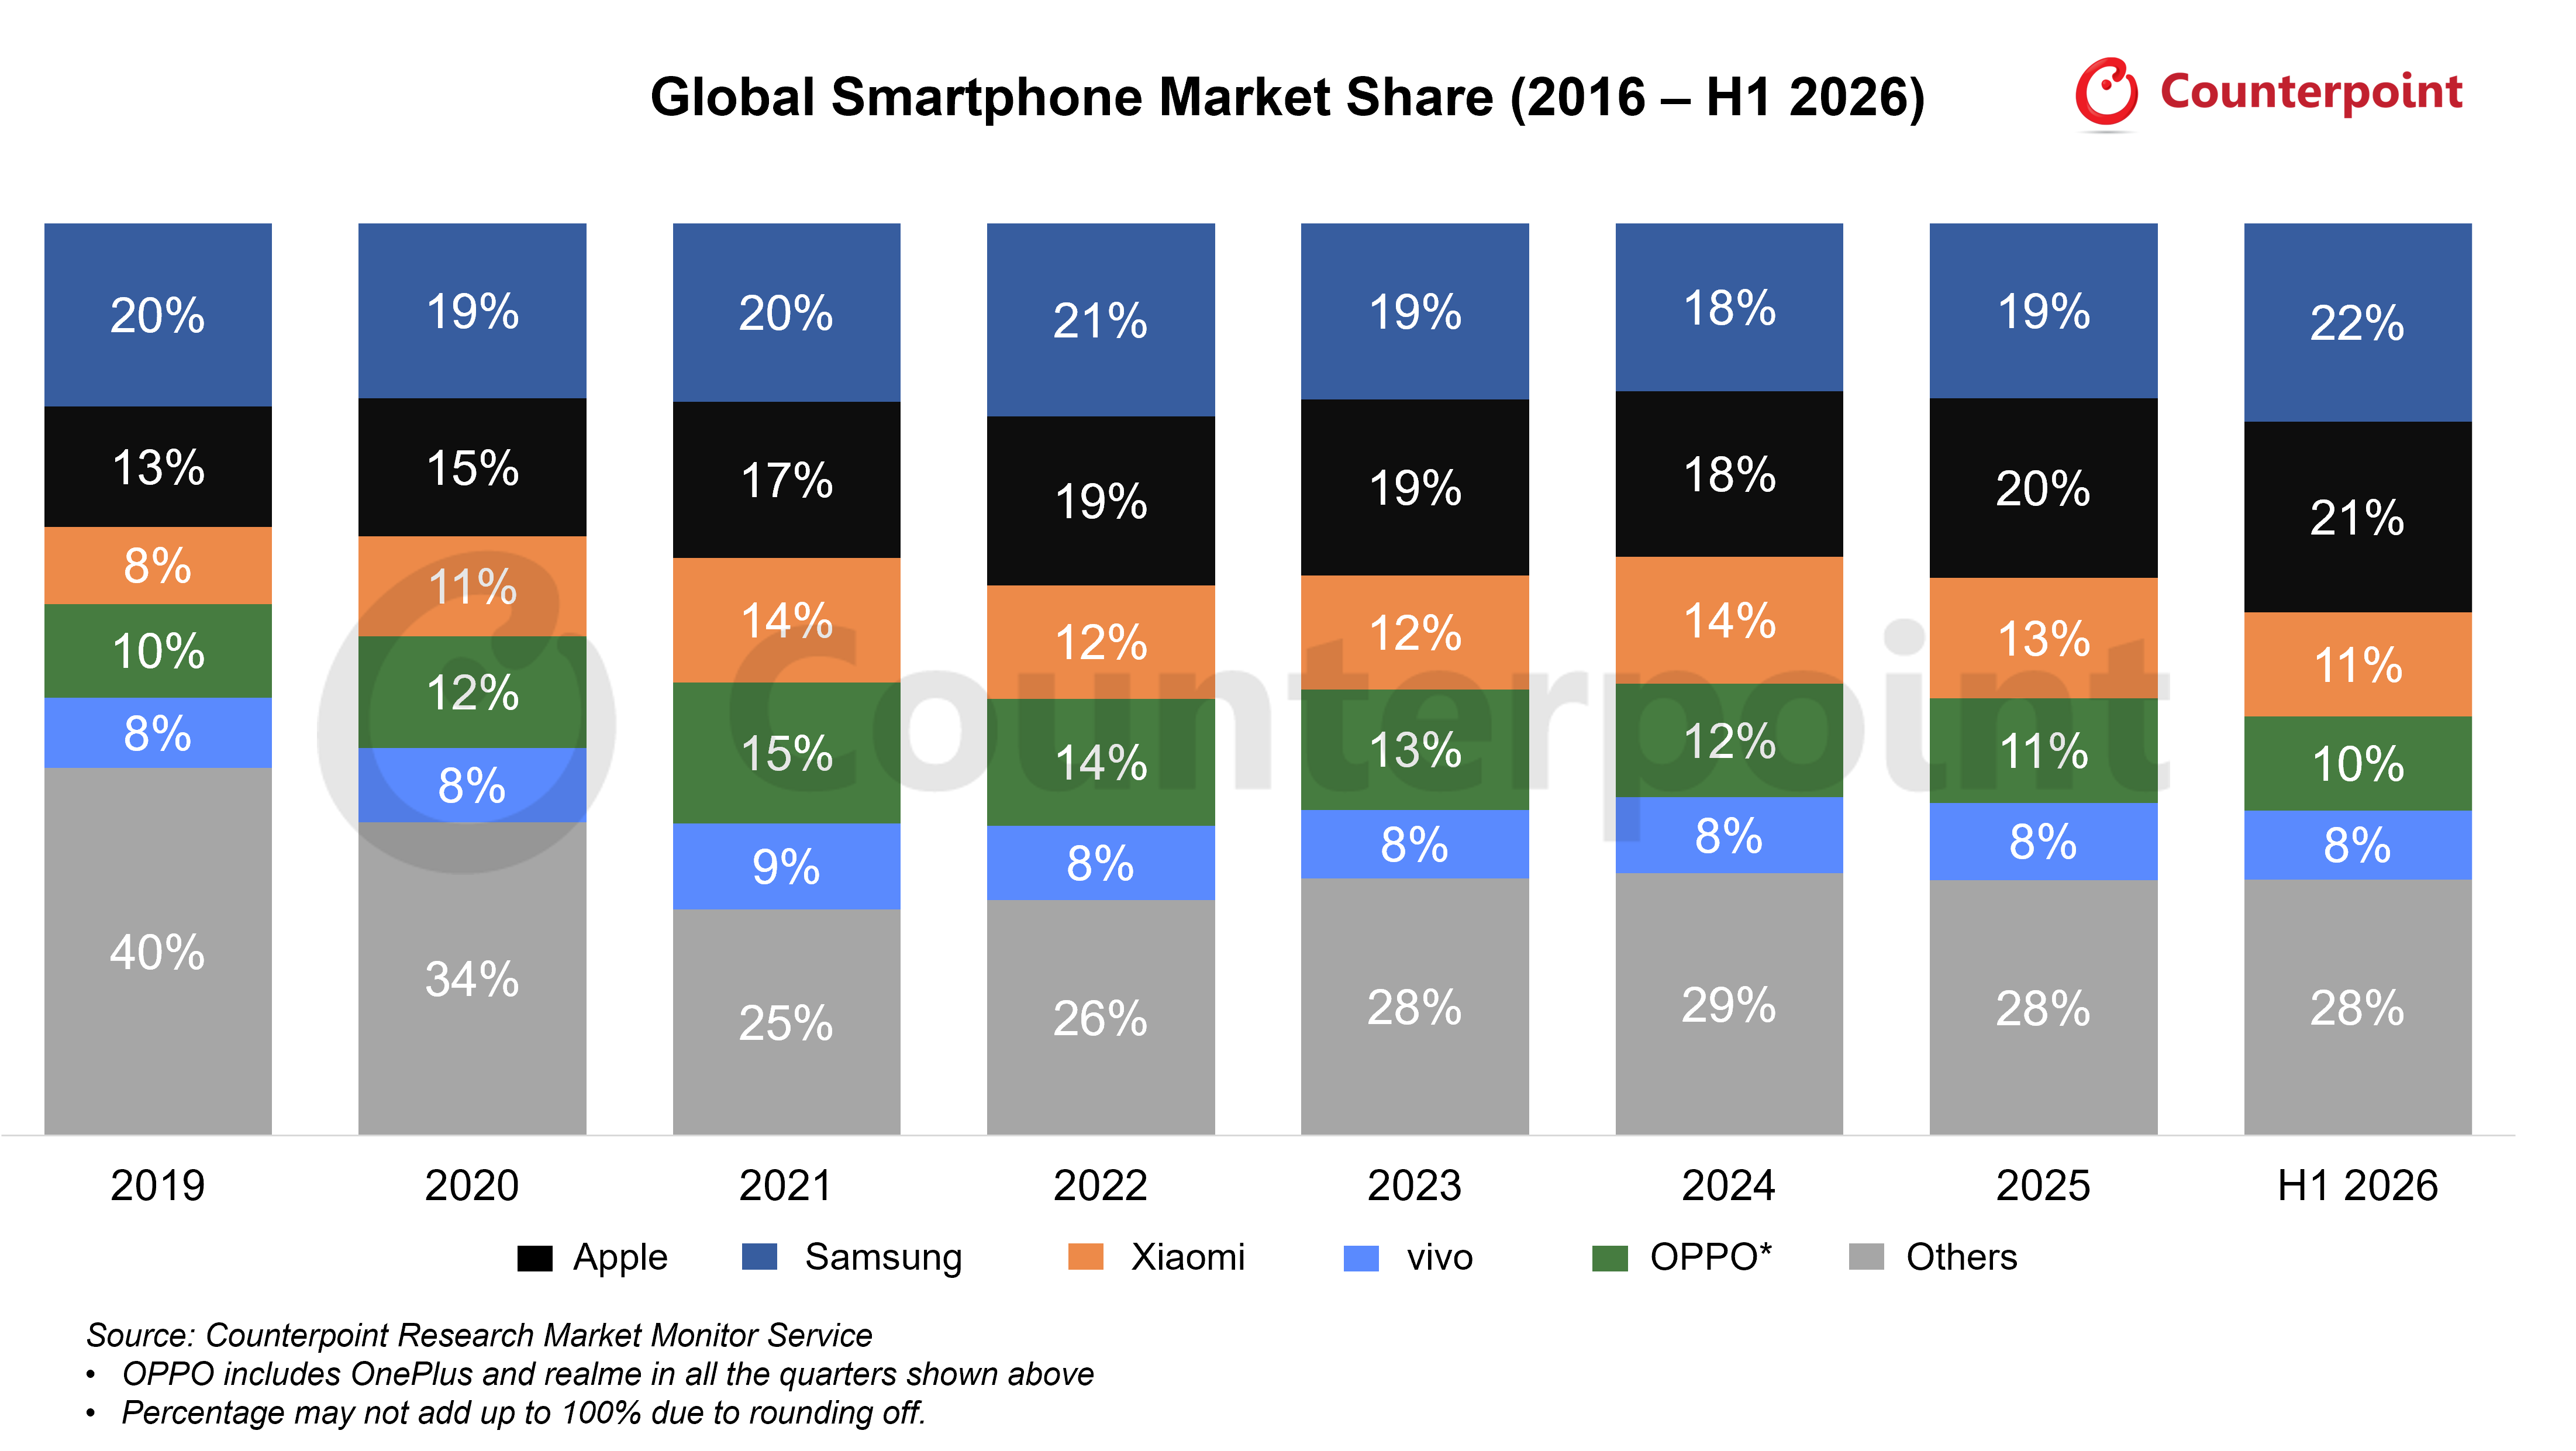
| Brands | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | H1 2026 |
| Samsung | 20.1% | 19.2% | 19.6% | 21.2% | 19.3% | 18.4% | 19.2% | 21.8% |
| Apple | 13.2% | 15.1% | 17.1% | 18.5% | 19.3% | 18.2% | 19.7% | 20.9% |
| Xiaomi | 8.4% | 10.9% | 13.7% | 12.4% | 12.5% | 13.9% | 13.2% | 11.4% |
| OPPO* | 10.3% | 12.3% | 15.5% | 13.9% | 13.2% | 12.5% | 11.5% | 10.3% |
| vivo | 7.7% | 8.2% | 9.4% | 8.2% | 7.5% | 8.3% | 8.5% | 7.6% |
| Others | 40.3% | 34.3% | 24.8% | 25.8% | 28.2% | 28.7% | 28.0% | 28.1% |
MARKET HIGHLIGHTS
- The global smartphone market declined 7% YoY in Q2 2026 as memory shortages and rising prices intensified. Frontloaded shipments by some OEMs softened the decline.
- Developed markets remained resilient due to higher premium exposure. North America grew 6% YoY, while Western Europe declined just 1%.
- Samsung reclaimed the global lead with 23% share and 9% YoY growth, supported by favorable pricing and competitive dynamics.
- Apple grew 13% YoY to its highest Q2 share of 21%, driven by the iPhone 17 series. It was also the only major OEM to avoid price hikes.
- Xiaomi declined 26% YoY, the steepest drop among the top five, as its entry and mid tier exposure amplified the impact of rising memory costs and weaker affordability.
The global smartphone market share numbers are from:
Market Monitor - OEM Shipment by Region and Countries, Q2 2026
Excel File | Published Date: August 2026
This report is part of a series of market monitor reports which track the mobile handset market: Smartphone and Feature Phone shipments every quarter for more than 140 brands covering more than 97% of the total device shipments in the industry.
Receive our insightful weekly newsletter and stay ahead of the competition.
Author
Team Counterpoint


Counterpoint Research is a global industry and market research firm providing market data, intelligence, thought leadership and consulting across the technology ecosystem. We advise a diverse range of global clients spanning the supply chain – from chipmakers, component suppliers, manufacturers and software and application developers to service providers, channel players and investors. Our veteran team of analysts serve these clients through our offices located across the key innovation hubs, manufacturing clusters and commercial centers globally. Our analysts consistently engage with C-suite through to strategy, market intelligence, supply chain, R&D, product management, marketing, sales and others across the organization. Counterpoint’s key coverage areas: AI, Automotive, Cloud, Connectivity, Consumer Electronics, Displays, eSIM, IoT, Location Platforms, Macroeconomics, Manufacturing, Networks & Infra, Semiconductors, Smartphones and Wearables.