

- Global smartphone sell-through volumes are expected to decline 1% YoY in February, with YTD volumes down 4% YoY. The decline is partly due to a slowdown in demand in the lower and mid range segments due to price increases.
- Counterpoint has observed noticeable price increases across most Android brands, like Samsung, Xiaomi, OPPO, vivo, realme and Transsion Group, as of February 2026.
- Most significant price increases have appeared in India, Southeast Asia, and Africa so far.
- Global smartphone ASPs are expected to grow 12% YoY for the full year 2026.
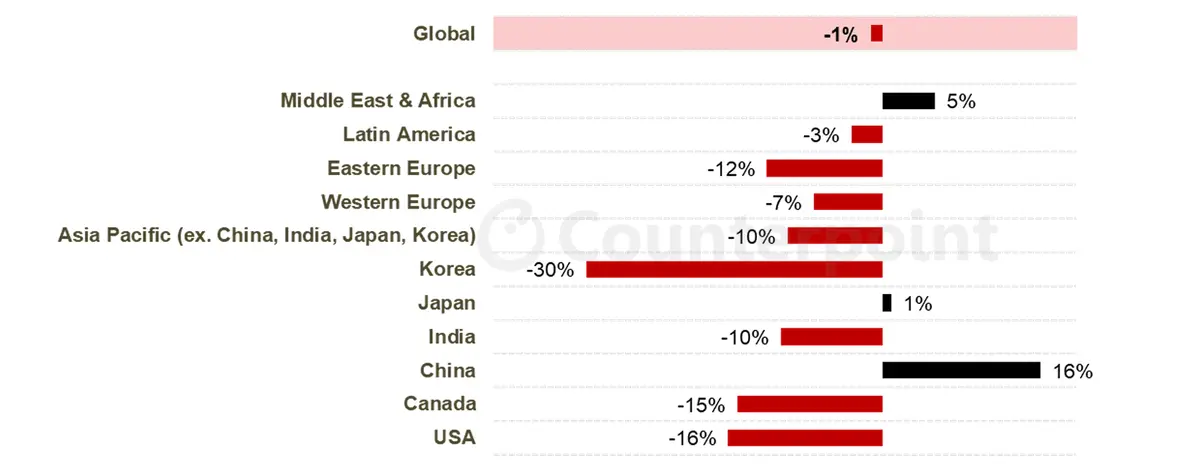
As per Counterpoint’s latest Market Pulse (Early Look), Global smartphone sell-through volumes are expected to decline 1% Year-on-Year (YoY) in February, as Lunar New Year promotions in China partially offset declines in other regions. Only the Middle East and Japan are also expected to grow YoY for the month, while Africa is expected to be flat YoY.
In terms of Year-to-Date (YTD, Jan-Feb) sell-through volumes, the market decline is more significant across regions, with the global volumes down 4% YTD. Some of the YTD decline is attributable to Samsung’s late launch of the S26 series and the weakness in the China market. However, demand is also slowing in the lower and mid-tier segments across markets due to price increases as a result of the increasing intensity of the memory crunch. Price changes are starting to trickle into more regions and price bands, despite best efforts from OEMs to mitigate sticker shock. Markets with a price sensitive buyer base will see increasing headwinds from the memory crisis from now on.
Smartphone Market Growth by Regions (%) - Year-on-Year
(February 2026 vs 2025)
Source: Counterpoint Research Market Pulse Midmonth (Early Look)


