India’s Road to Semiconductor Self-Reliance: From Manufacturing Chips to Building Complete Ecosystem
0
September 14, 2026
India’s semiconductor market is expected to cross $130 billion by 2030.
The Indian government’s Semicon 1.0 program focused on the physical foundation of the country’s semiconductor ecosystem, whereas Semicon 2.0 focuses on establishing the ecosystem around it.
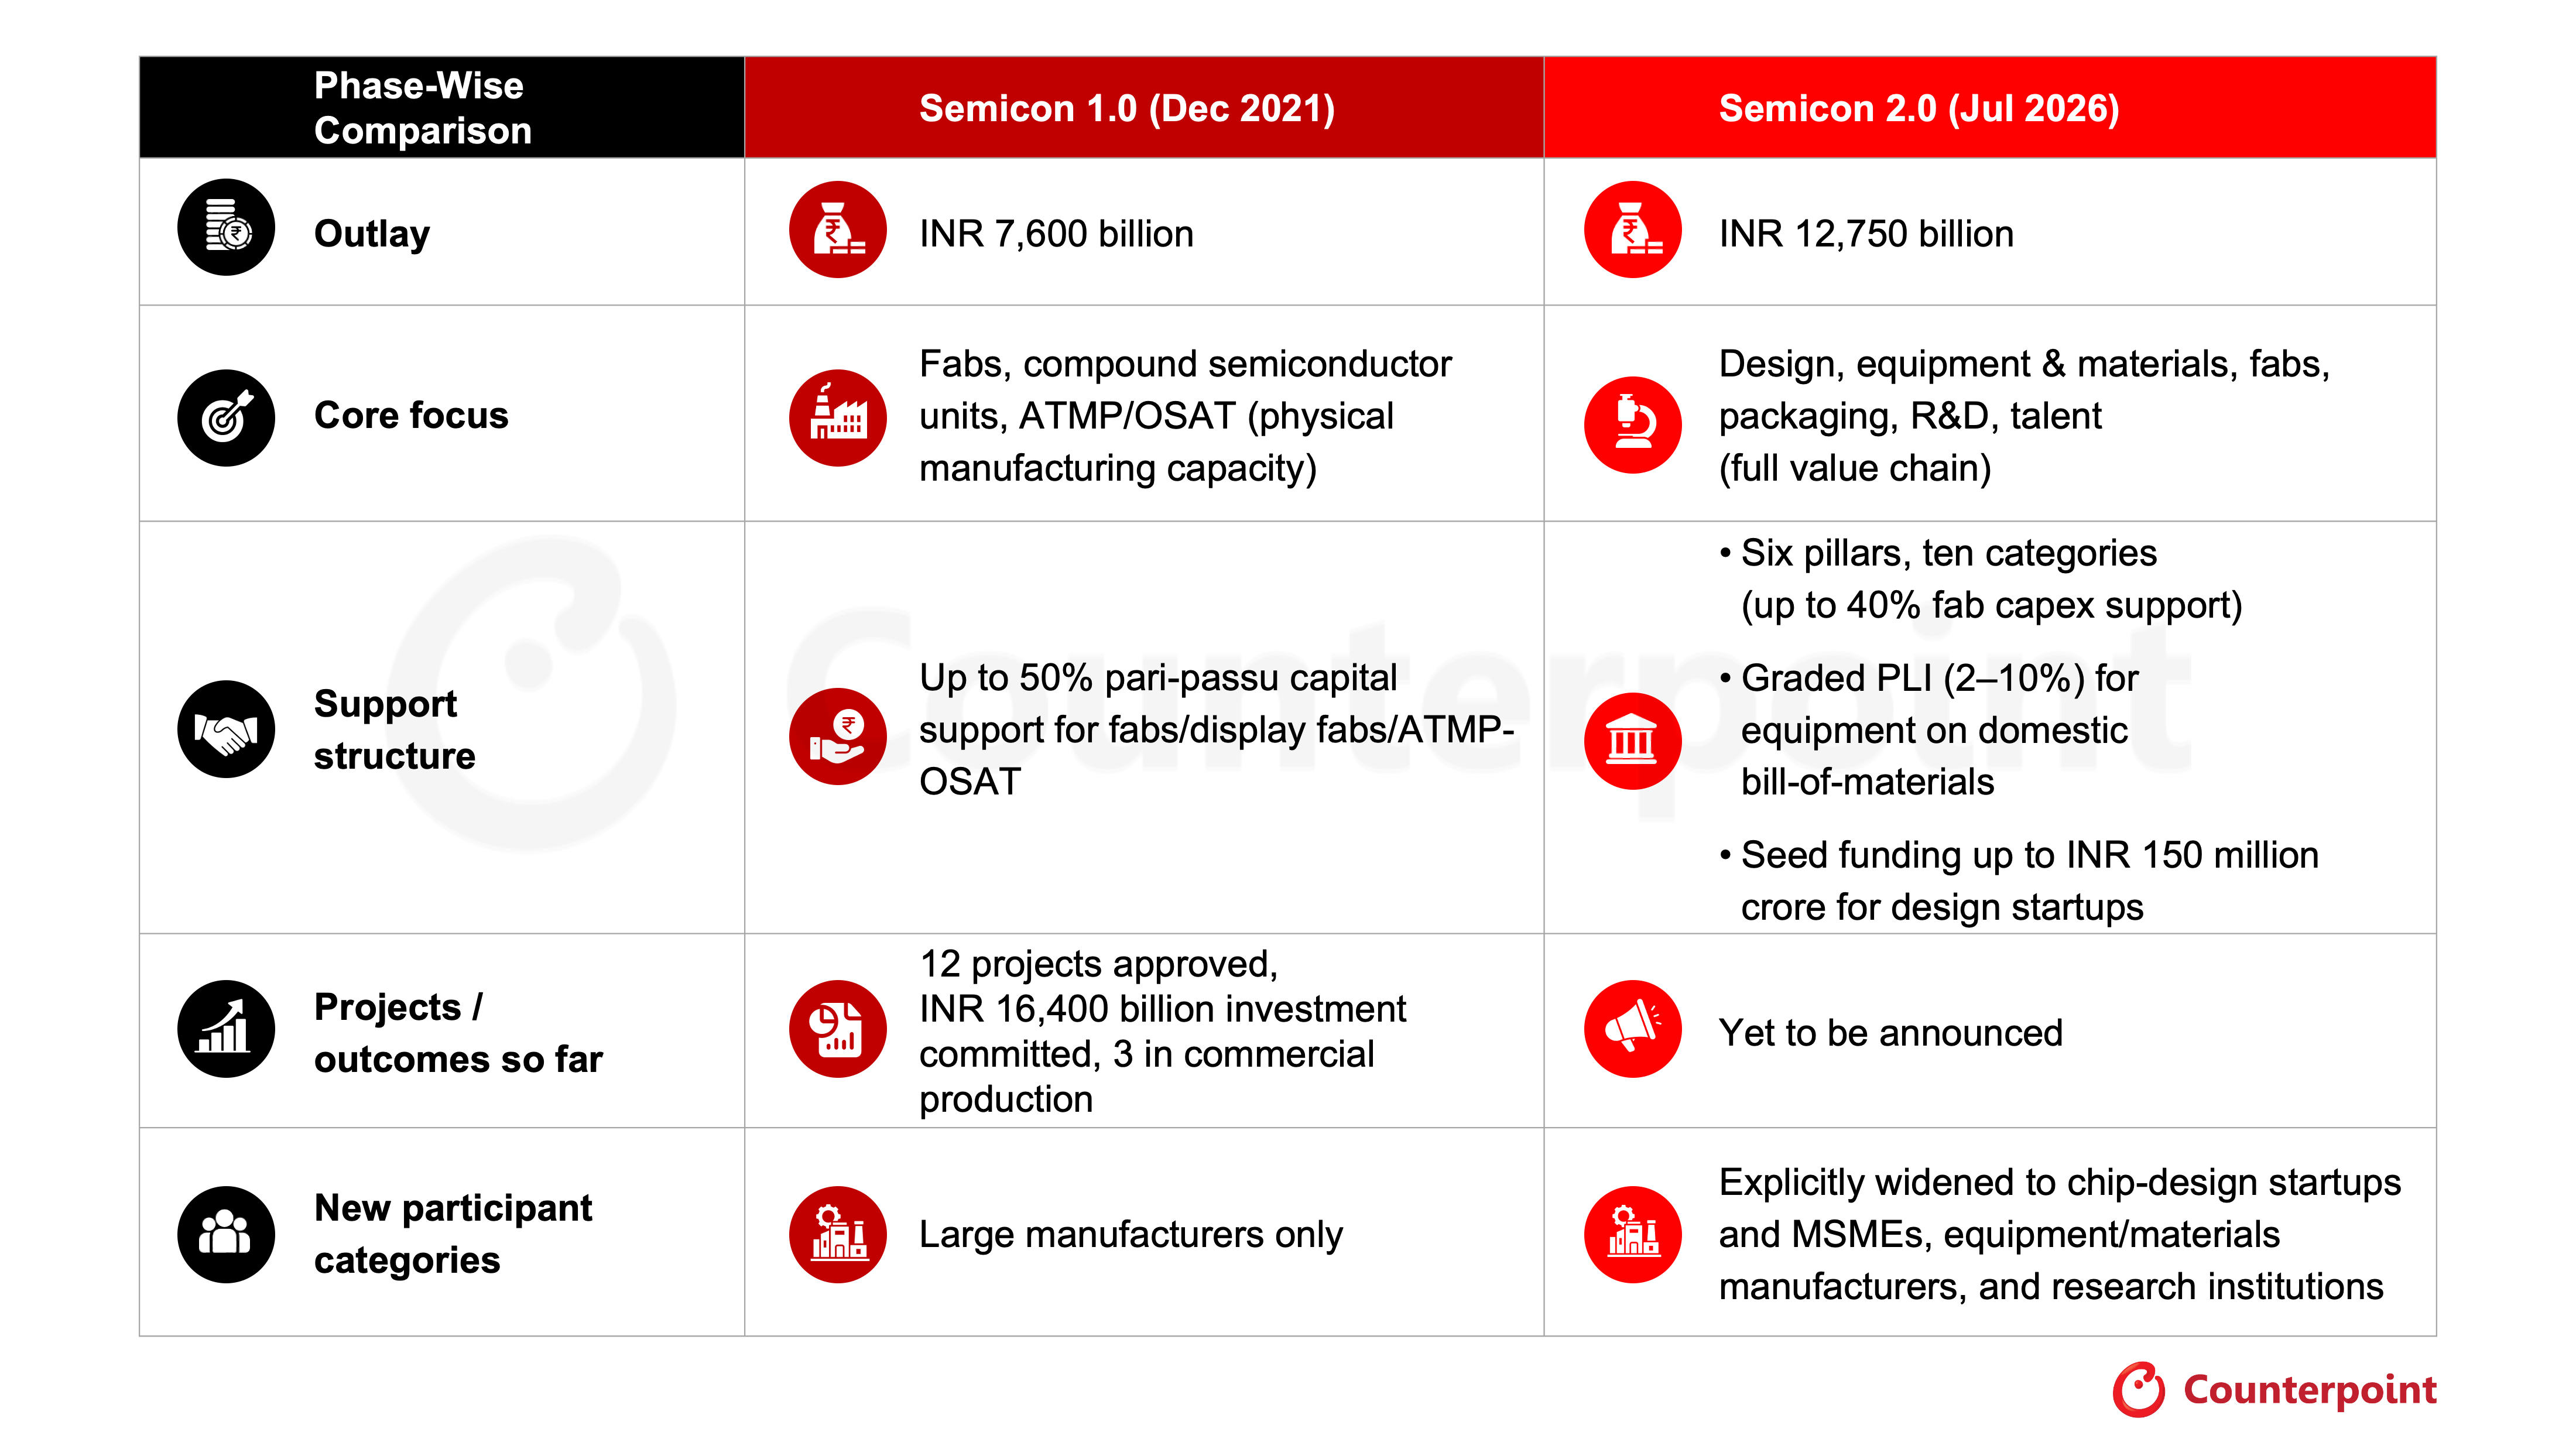
The outlay for Semicon 2.0 is around 68% higher than Semicon 1.0, with emphasis on design, equipment and materials, fabrication, packaging, R&D and talent.
India’s semiconductor ecosystem is entering an important phase of growth. According to Counterpoint Research, the country’s semiconductor market is expected to cross $130 billion by 2030. More than 90% of India’s semiconductor demand has historically been met through imports, despite the country’s strong chip-design talent base. Reducing this dependence was a key objective behind the launch of Semicon 1.0 program by India’s government in 2021. More than 10 semiconductor projects have been approved under the program, involving more than $20 billion in committed investments. Now, with the launch of Semicon 2.0 in 2026, the government is broadening its approach.
Semicon 1.0 was primarily about establishing the physical foundation of India’s semiconductor industry. The focus was on attracting large investments into fabs, ATMP/OSAT and other semiconductor manufacturing infrastructure. This was necessary because India had limited domestic semiconductor manufacturing capacity.
But building fab/OSAT plants alone does not create a semiconductor ecosystem. A fab needs a supporting network of chip designers, IP companies, equipment and materials suppliers, packaging capabilities, R&D institutions and, most importantly, specialized talent. Without these layers, a significant portion of the value chain can still remain dependent on imports.
Semicon 2.0 recognizes this gap and broadens the strategy from “building semiconductor plants” to building the ecosystem around them. Its focus extends across design, equipment and materials, advanced packaging, R&D, manufacturing and talent development.
Semicon 1.0 vs Semicon 2.0
What is different about Semicon 2.0?
Semicon 2.0 has been approved with an outlay of INR 12,750 billion, nearly 68% higher than the INR 7,600 billion allocation under Semicon 1.0. The bigger change, however, is not just the size of the allocation; it is the wider scope of the program. The focus now extends across design, equipment and materials, fabrication, packaging, R&D and talent.
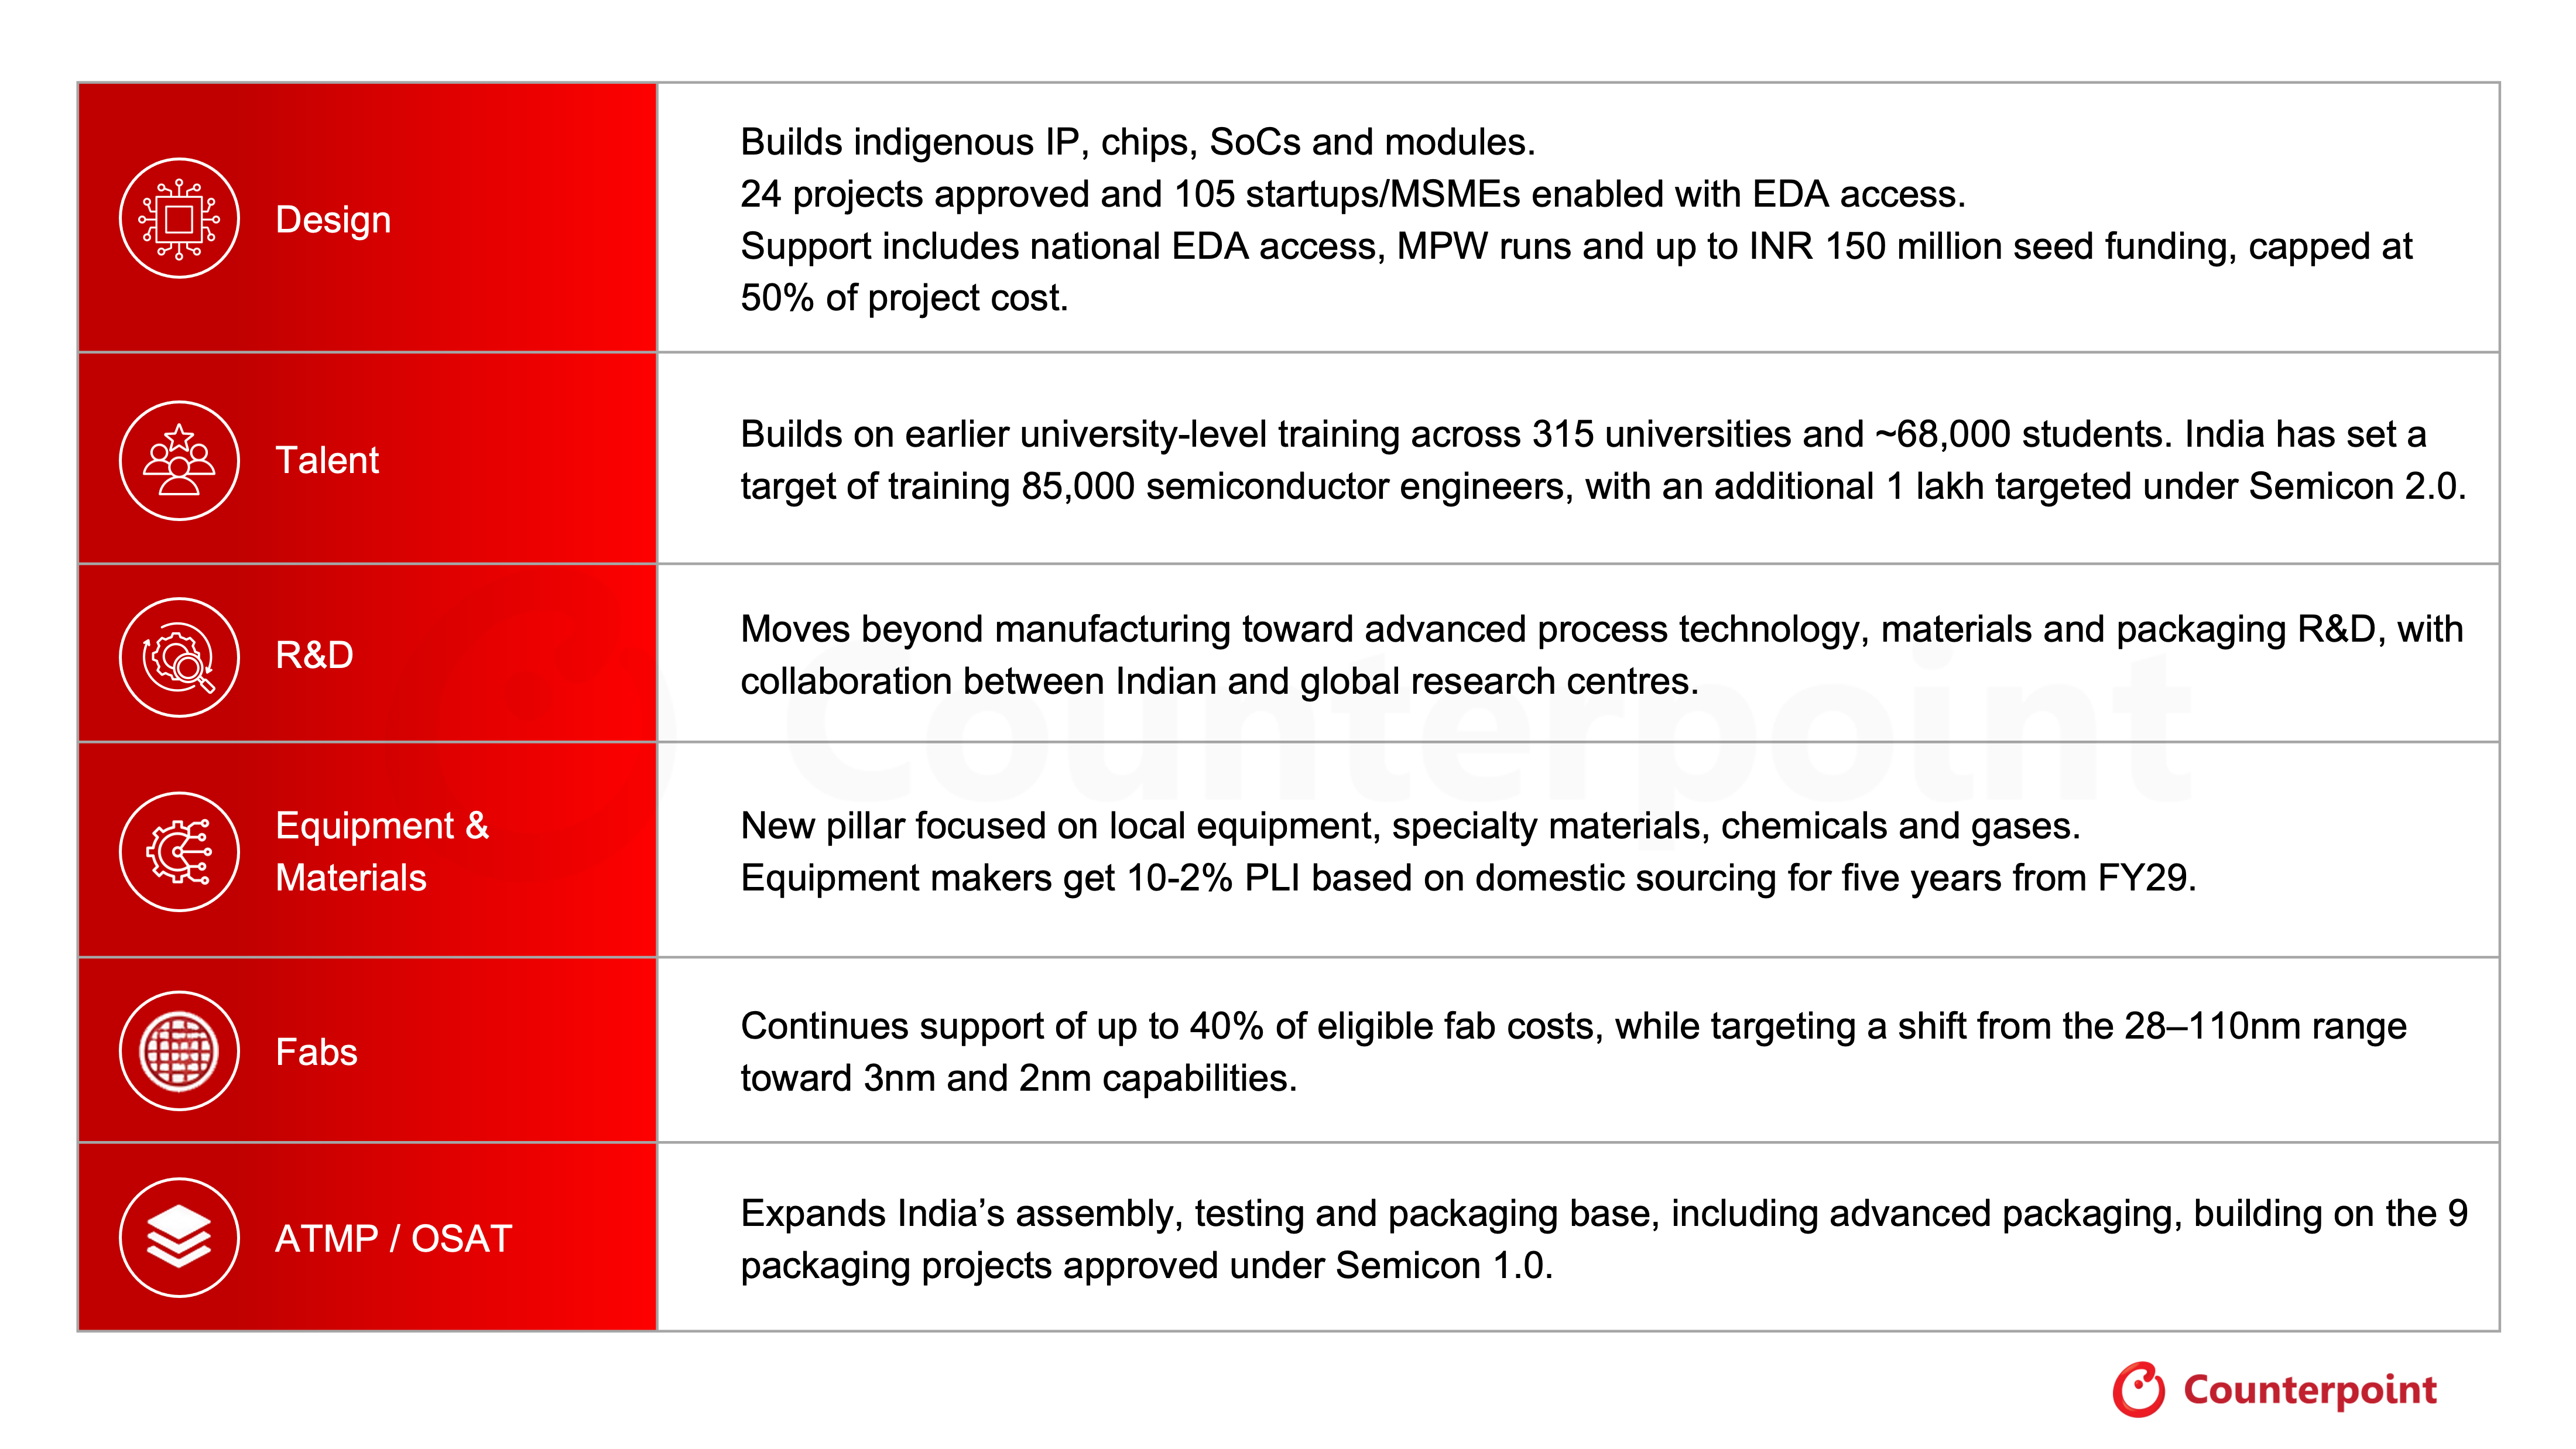
The framework is built around six key pillars:
What Semicon 2.0 changes
Chip design
While manufacturing capabilities are still being built, design is where India already has a significant advantage, with more than 20% of the global semiconductor design workforce based in the country. This talent supports the R&D and design operations of global majors such as Intel, Qualcomm, AMD, NVIDIA, MediaTek, Texas Instruments, Broadcom, Marvell, NXP and STMicroelectronics.
The strategic opportunity now is to move from being a major design services and R&D hub to an owner of semiconductor IP and products. Semicon 2.0 aims to support this transition by encouraging the development of indigenous IP, chips, SoCs and modules. Under the program, 24 projects have been approved, while 105 startups and MSMEs have been enabled with EDA access. This means building the capability to take designs beyond development and simulation into manufacturing (tape-out), testing and validation, particularly in areas such as AI, telecom, IoT, drones and satellite communications. In that sense, Semicon 2.0 is not just about creating more designers, it is about capturing more value from the design talent India already has.
Talent
However, as fabs and OSAT facilities move from announcements toward operations, the challenge is shifting from having semiconductor talent to building production-ready capability. The next opportunity is to build practical skills across the full chip-development process, from chip design and design tools to tape-out, testing, packaging and manufacturing. Academic programs can provide a good foundation in VLSI, but practical and lab experience is needed to turn this knowledge into a working chip with real industry tools, processes and projects. Initiatives such as DLI and C2S, along with industry-led programs from Synopsys, Cadence, Siemens EDA and Lam Research, are helping bridge this gap by expanding access to tools, laboratories and practical training. These efforts build on earlier university-level training across 315 universities and ~68,000 students. India has also trained around 85,000 semiconductor engineers, with an additional 100,000 engineers targeted under Semicon 2.0. Capability building is also extending beyond chip design into areas such as nanofabrication, packaging and validation.
This is a key part of the Semicon 2.0 vision. The goal is no longer simply to attract semiconductor investments, but to develop the practical skills needed to capture more value from them. The depth of this capability will ultimately determine how much of India’s semiconductor value chain can be built and owned domestically.
R&D
Semicon 2.0 gives greater focus to semiconductor R&D. The program supports research in areas such as advanced process technologies, new materials, semiconductor devices and advanced packaging, while encouraging collaboration between Indian and global research centres. India already has a strong semiconductor R&D base, with global companies such as AMD, NVIDIA, Qualcomm, Intel and Applied Materials operating R&D and engineering centres in the country. Building on this existing ecosystem can help India develop more homegrown semiconductor technologies and strengthen its position in semiconductor innovation.
Equipment and materials
Equipment and materials are the backbone of semiconductor manufacturing. Fabs need specialized machines and critical inputs such as silicon wafers, specialty chemicals, gases and photoresists. India currently imports more than 90% of its semiconductor manufacturing equipment, leaving a major gap in the domestic supply chain. Semicon 2.0 aims to reduce this dependence by offering 30% support on eligible capital expenditure for manufacturing semiconductor equipment, materials, chemicals and gases. Equipment manufacturers can also receive a PLI (performance-linked incentive) of 2% to 10% over five years, linked to their domestic sourcing.
Fabs
Semicon 1.0 had a major focus on building semiconductor manufacturing capabilities, especially fabs and packaging facilities, but Semicon 2.0 takes a broader approach by supporting the wider semiconductor ecosystem. Fabs remain a key pillar because India needs more domestic chip manufacturing capacity to reduce its dependence on imports. Under the current framework, the government offers flat fiscal support of 40% to 50% of the capital expenditure across all technology nodes. This uniform structure is aimed at encouraging investments in both advanced leading-edge and mature legacy semiconductor manufacturing.
ATMP/OSAT
Semicon 1.0 gave a major push to ATMP and OSAT facilities, with the government providing 50% of capital expenditure support on a pari-passu basis. This helped attract investments from companies such as Micron, Tata Electronics and CG Power. By early 2026, eight packaging units had been approved under the program, covering areas including memory, advanced packaging and silicon-carbide packaging. Semicon 2.0 further strengthens this capacity, supporting the adoption of more advanced packaging technologies. This can help increase domestic value addition and support the growth of India’s electronics manufacturing industry.
Road ahead
India’s semiconductor story is now moving from building capacity to building capability. With Semicon 2.0, the focus is shifting toward creating a stronger ecosystem across design, manufacturing, equipment, materials, packaging, R&D and talent. If these efforts come together, India can move beyond being a large semiconductor consumer and manufacturing base to becoming a more integrated and globally relevant part of the semiconductor value chain.
Receive our insightful weekly newsletter and stay ahead of the competition.
Author
Shivani Parashar
Shivani is a market researcher with over 11 years of market research and consumer insights experience. She started her career with Northern Trust Corporation and has since worked with multiple other market research & consulting agencies in India. Shivani has worked across a wide variety of industries, including but not limited to, technology, automotive, and logistics. She has handled multiple end-to-end research project across industries & functions covering a wide variety of subjects. Within Counterpoint, she focuses on components, especially semiconductor foundries and chipsets. Shivani holds an MBA degree in Marketing and an Engineering Degree in Electronics & Instrumentation.