- European smartphone shipments dropped to their lowest quarterly total for over thirteen years following an 18% YoY decline in Q3 2026.
- Component cost hikes resulted in higher final device prices and a scaling back of promotions, while a challenging macro climate continued to impact consumer demand.
- Some high-profile premium launches helped limit the drop for the likes of Apple and Samsung, although lower-end weakness still resulted in a YoY decline for both.
- Chinese OEMs, meanwhile, are being hit the hardest in Europe, and many are rethinking their strategies.
- With component prices not expected to stabilise until the middle of next year, it will likely still be a difficult Christmas for smartphone manufacturers in Europe.
London, Berlin, Beijing, Buenos Aires, Fort Collins, Hong Kong, New Delhi, Seoul, Taipei, Tokyo – November 19, 2026
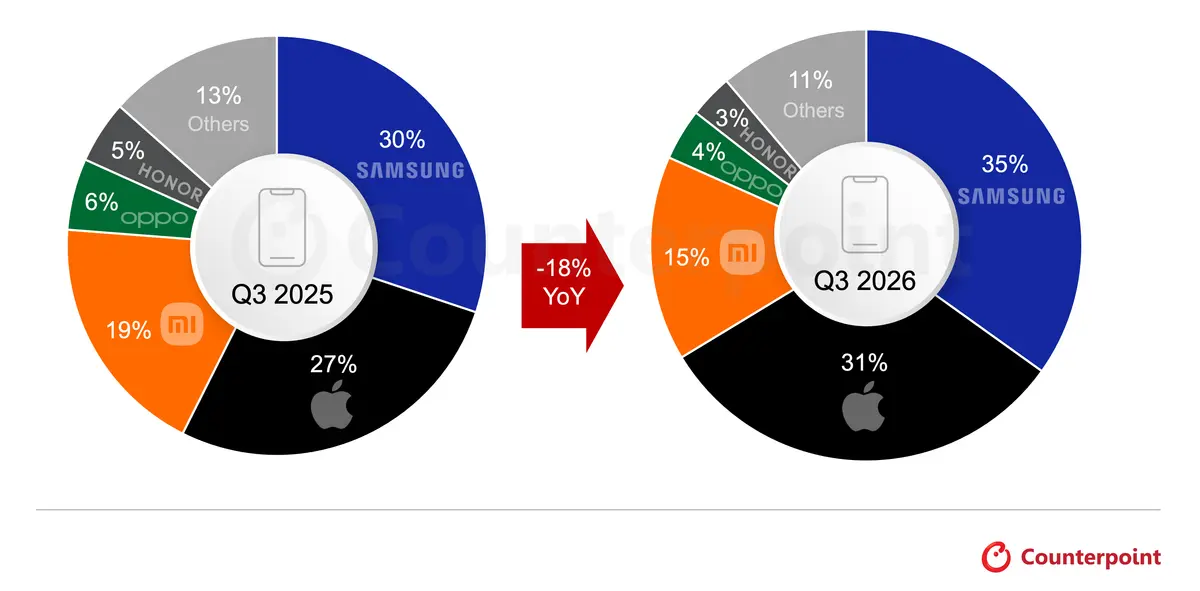
Europe Smartphone Shipments Share by OEM, Q3 2025 vs Q3 2026
Source: Counterpoint Research Market Monitor Q3 2026
Note: OPPO includes OnePlus and realme. Percentage totals may not add up to 100%
Europe’s smartphone market dropped to its lowest quarterly total for over thirteen years following an 18% YoY decline in Q3 2026, according to Counterpoint Research’s Q3 2026 Smartphone Market Monitor. Component cost hikes resulted in higher final device prices and a scaling back of promotions, while a challenging macro climate continued to impact consumer demand.
Associate Director Jan Stryjak said, “Despite some high-profile launches across the region, Q3 was very challenging for the European smartphone market. The new passport-sized Galaxy Z Fold8 was Samsung’s fastest-selling foldable in Western Europe ever, but it couldn’t make up for weakness in its Galaxy A series. Meanwhile, Apple made headlines with the launch of its first foldable, the iPhone Duo. But with the device not hitting the shelves until October and the base iPhone not launching until Q1 2027, Apple recorded its first YoY decline in Europe since Q1 2024. Chinese OEMs are being hit the hardest in Europe, and many are rethinking their strategies. Margin protection is of paramount importance, but so is survival. Most have so far relied heavily on the region’s rapidly dwindling budget tiers, so some are therefore looking at niche customer segments to target (such as camera or gaming enthusiasts), or are concentrating their efforts on a few high-value markets rather than a pan-regional approach.”
Stryjak added, “Q4 is typically the best quarter for smartphone shipments, and there is no reason to think this year will be any different. But with component prices not expected to stabilise until the middle of next year, it will likely still be a difficult Christmas for smartphone manufacturers in Europe.”
About Counterpoint Research
Counterpoint Research is a global market research firm specializing in products across the technology ecosystem. We advise a diverse range of clients – from smartphone OEMs to chipmakers and channel players to Big Tech – through our offices located in the world's major innovation hubs, manufacturing clusters and commercial centers. Our analyst team, led by seasoned experts, engages with stakeholders across the enterprise – from the C-suite to professionals in strategy, analyst relations (AR), market intelligence (MI), business intelligence (BI), product and marketing – to deliver services spanning market data, industry thought leadership and consulting. Our core areas of coverage include AI, Automotive, Consumer Electronics, Displays, eSIM, IoT, Location Platforms, Macroeconomics, Manufacturing, Networks and Infrastructure, Semiconductors, Smartphones and Wearables. Visit our Insights page to explore our publicly available market data, insights and thought leadership, and to understand our focus, meet our analysts and start a conversation.
Follow Counterpoint Research


