
AMD Q3 26 revenue came in at $13.4B, up 45% YoY and above $13.0B guide. Data center is now 64% of revenue, up from 47% a year ago, and will be over 80% next year. Data center revenue reached $8.5B, up 97% YoY, with segment operating margin rising to 34% from 25%.
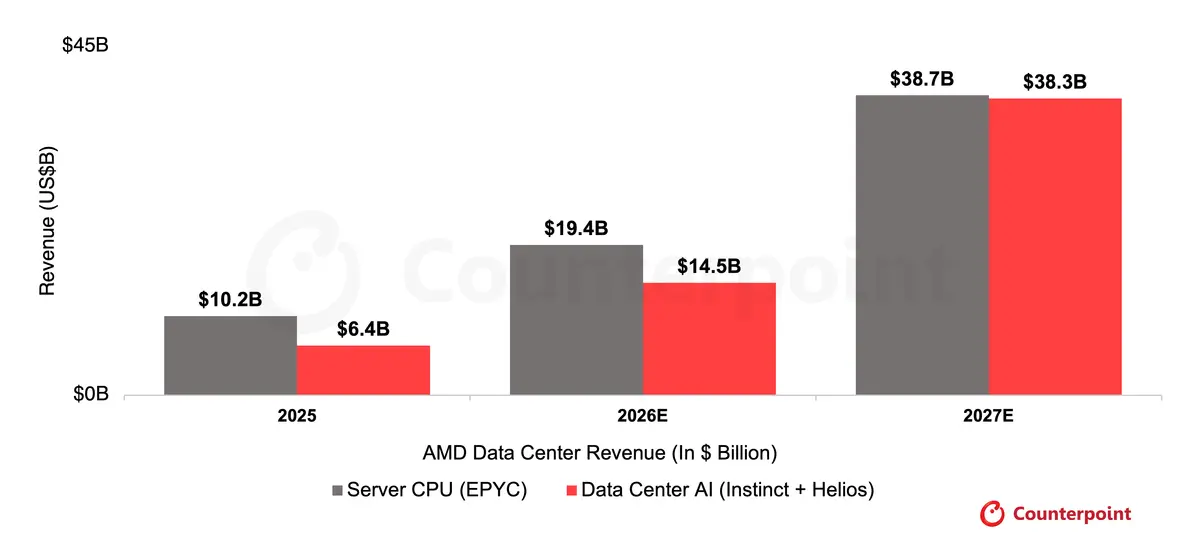
- Outlook. Q4 guidance of ~$17B (+66% YoY) is ~$800M above consensus, with data center expected to grow ~50% sequentially. Q4 is set to be the first quarter in which DC AI passes server CPU in dollars, driven by the Helios ramp. AMD also raised its 2027 view further: total revenue growth of more than 80%, server roughly doubling (up from >70% last quarter), DC AI significantly more than doubling, and data center above 80% of revenue. By our estimate, that is ~$77B of data center revenue in 2027.
- Agents drive CPU: Server CPU is the harder 2027 target. At its Q4 run-rate, AMD’s server business makes ~$24B a year; the 2x goal needs ~$39B, about 60% more. AI starts closer to its goal and needs only ~40% more. Cloud and enterprise server sales each more than doubled YoY in Q3, and Turin is now the most deployed EPYC generation in public cloud, with 540+ instances. Venice began revenue shipments with 240+ OEM platforms, 20% more than Turin.
- CPU racks and head nodes: The new Helion rack holds up to 144 Venice CPUs and ~74k threads, the first CPU-only rack built for agents, with first systems shipping in Q4. AMD also gets paid on the custom-chip path: OpenAI is using Turin as the host CPU for its ASIC, and several model developers and clouds have signed head-node deals that ramp over the coming quarters.
AMD Data Center: ~$77B in 2027E, Split Evenly CPU vs AI
Source: Company reports, Counterpoint Research estimates
AMD vs Intel Analysis
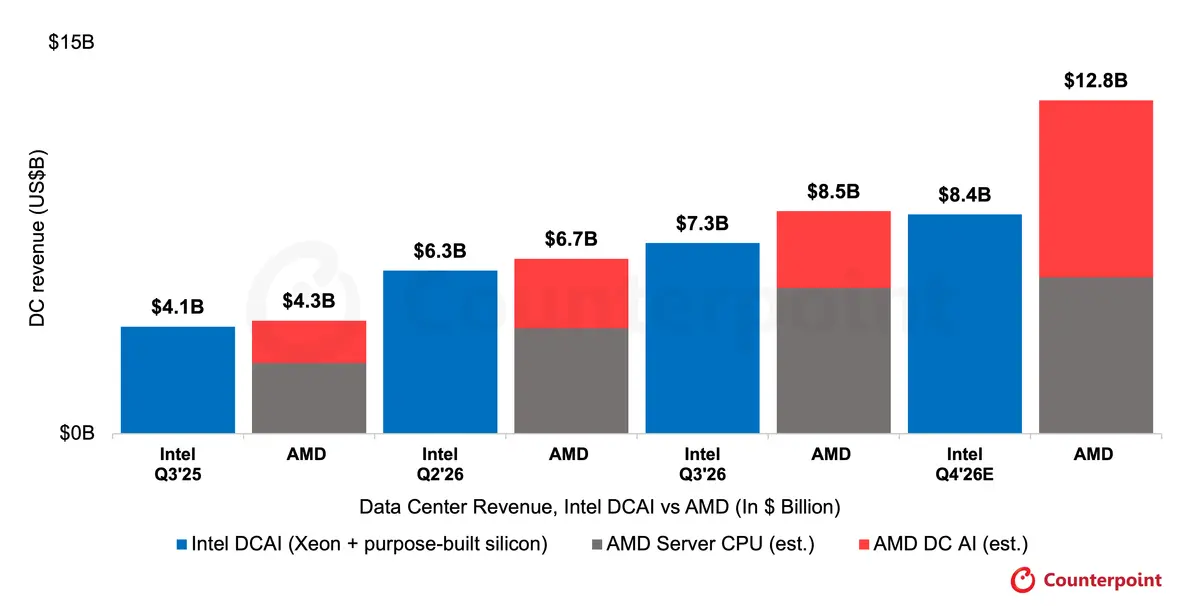
- AMD is guided to out-revenue Intel in Q4: ~$17B vs Intel’s ~$15.5B midpoint. Even AMD’s low end beats Intel’s high end, and the gap is almost entirely data centre.
- AMD’s data center lead over Intel comes from AI (GPUs and racks), not CPUs. AMD DC was $8.5B vs Intel DCAI at $7.3B in Q3, but take out Instinct and Intel is still bigger in server. Intel’s DCAI grew 78% YoY, its strongest growth in 15 years, with Granite Rapids on Intel 3 ramping fast and Clearwater Forest on 18A shipping for revenue.
- In 2026, AMD is holding server CPU share rather than taking it rapidly. 2027 is the key year: Intel expects server CPU units to grow more than 30%, while AMD guides server revenue to roughly double, mostly from units. That points to meaningful x86 share gains for AMD.
- On margins, Intel’s DCAI operating margin (41.5%) beats AMD’s DC margin (34%), but AMD’s is diluted by HBM-heavy Instinct GPUs; AMD’s server CPU margin alone likely tops Intel’s. At the company level, AMD’s 56% gross margin vs Intel’s 44% (38% guided for Q4) reflects AMD’s fabless model against Intel Foundry losses.
- Both companies are supply-constrained, but differently. Intel expects shortages through 2027 into 2028, is short on Intel 3 wafers and substrates, and is absorbing the Fab 28 incident. AMD relies on TSMC and has secured supply for 2027’s >80% growth.
Data Center: AMD Pulls Ahead on the Back of AI
Source: Company reports, Counterpoint Research estimates
Bottom line: the question for 2027 is no longer demand. It is who can ship.
Full analysis on Counterpoint Cloud AI Research: https://counterpointresearch.com/en/reports/global-cloud-ai-gpu-cpu-compute-asic-report-q2-2026

