
- YMTC has filed for a Shanghai STAR Market IPO, following twin-star CXMT's blockbuster July 2026 debut.
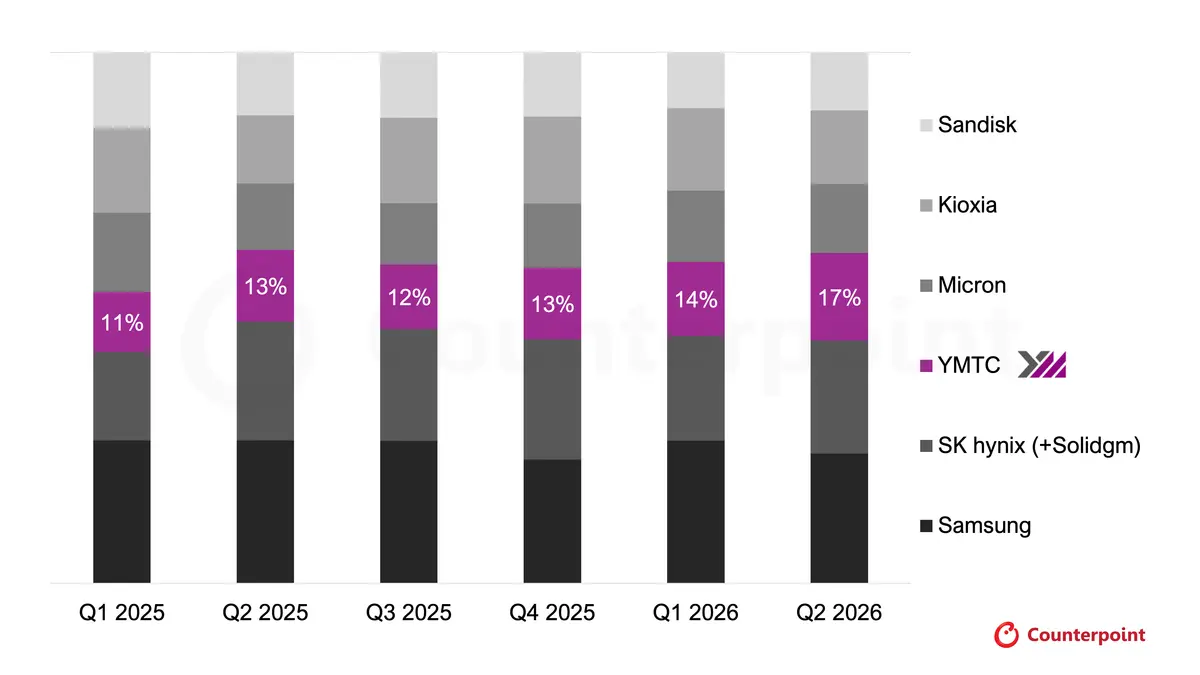
- The Wuhan-based chipmaker rose to No. 3 globally by NAND shipment volume in Q2 2026, trailing only Samsung and SK Hynix and ahead of Kioxia and Micron; stripping out SK Hynix's Solidigm unit, YMTC already ranks No. 2 by volume.
- YMTC's NAND revenue share rose by more than half, from 9% to 14%, in four quarters (Q1 2025 to Q1 2026), with YoY revenue growth reaching as high as 478%.
- Enterprise SSD revenue, near zero in 2024, is projected to approach 39% of YMTC's total revenue by 2028 as AI data center rollout continues.
- The company is extending its proprietary Xtacking wafer-bonding technology beyond NAND into DRAM, aiming to move from being a domestic NAND commodity supplier toward next-generation AI memory.
Beijing, Berlin, Buenos Aires, Los Angeles, London, New Delhi, Seoul, Taipei, Tokyo – 13th October 2026.
Yangtze Memory Technologies Co. (YMTC), China's only NAND flash maker at commercial scale, has filed for an IPO on Shanghai's STAR Market, Counterpoint Research has confirmed, arriving roughly a month after twin-star CXMT's own STAR Market debut. The listing comes as YMTC's standing in the global NAND market has climbed rapidly.
The Wuhan-based chipmaker rose to No. 3 globally by shipment volume in the second quarter of 2026, according to Counterpoint Research's Memory Tracker and Forecast, now trailing only Samsung Electronics and SK Hynix and moving ahead of Japan's Kioxia and US-based Micron Technology. If SK Hynix's volumes are unbundled from its Solidigm subsidiary, YMTC's position climbs further still, to No. 2 globally by shipment volume.
Global NAND Market Share by Shipments
Source: Counterpoint Research Memory Tracker & Forecast
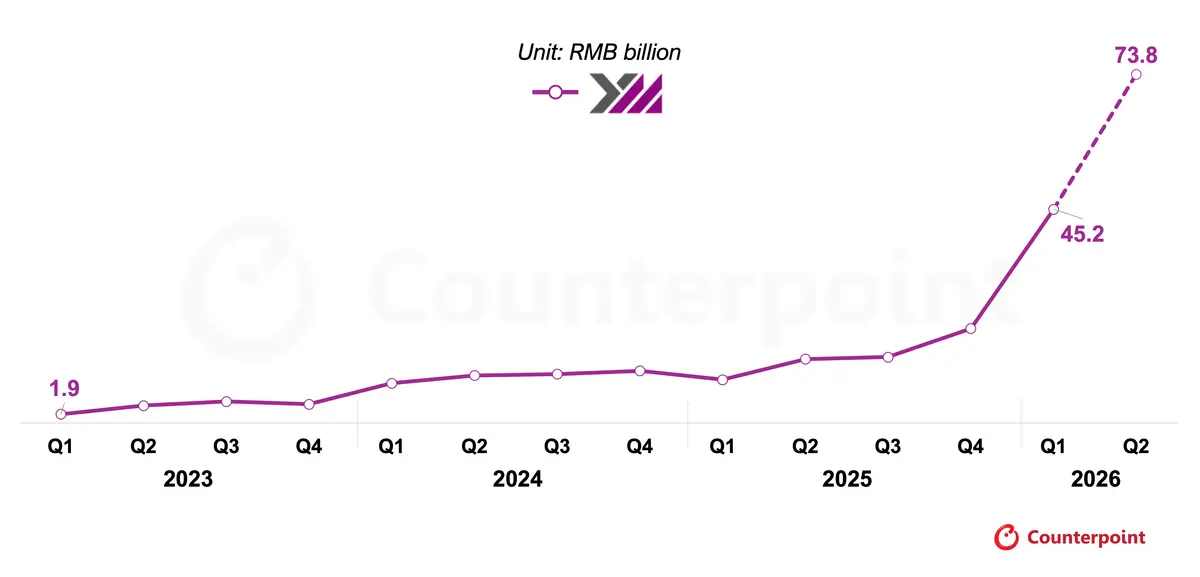
At the same time, YMTC's global NAND revenue share rose by more than half, from 9% in Q1 2025 to 14% in Q1 2026, the fastest-growing share gain of any major NAND vendor over that period, with year-over-year revenue growth reaching as high as 478% as AI-driven demand lifted the entire NAND market.
Commenting on YMTC’s growth spurt, Senior Analyst Jeongku Choi noted, “With AI driving the NAND super cycle, YMTC has become the fastest-growing vendor, with prudent investments in capability and capacity despite geopolitical headwinds. YMTC’s revenue in 2026 is bound to grow 6x faster than the industry and its peers.”
YMTC's Revenues : Q1 2023 - Q2 2026
Source: Counterpoint Research Memory Tracker & Forecast
Where the Growth Is Actually Coming From
Much of YMTC's momentum is tied to a segment it barely served two years ago: enterprise SSDs for AI data centers.
Research Director, MS Hwang, highlighted, “The company rides the upcycle on both price and domestic volume but has not been able to capture the full enterprise-SSD premium until now. However, we estimate server-related revenue, which was effectively zero in 2024, will reach close to 39% of total revenue by 2028. Key strategy will be to build out controller partnerships with Phison, DapuStor, Silicon Motion, DERA and T-Head, alongside a key domestic enterprise relationship with Huawei.
“The bigger question is whether YMTC can convert this into design wins with customers outside China, not just domestic hyperscalers. This will drive further impetus to the company to challenge the number one player Samsung.”
The IPO Backdrop
YMTC filed its Shanghai STAR Market IPO prospectus in August 2026, following its pre-IPO counselling (tutoring) registration and first-phase progress report earlier in the year. The float comes roughly a month after twin-star CXMT, China's leading DRAM challenger, made its own STAR Market debut on July 16, 2026, surging to a market value above CNY 3 trillion (about $443 billion) on its first day of trading, Counterpoint Research has previously reported. YMTC's own valuation and offer price have not yet been set.
Technology Edge Rivals Are Starting to Recognize
Behind the ranking climb sits YMTC's proprietary Xtacking architecture, which fabricates a chip's memory array and its peripheral logic circuitry on two separate wafers before fusing them together, letting each layer use the manufacturing process best suited to it.

Source: Counterpoint Research Memory Research, Sep 2026
Commenting on YMTC's technology capabilities, Research Vice President, Neil Shah said, “On the first floor of YMTC's Wuhan headquarters stands the "Patent Wall," a physical showcase of its independent intellectual property. The innovative approach, such as Xtacking, allows YMTC to keep adding layers using mature, non-cutting-edge lithography tools, a critical advantage as US export controls restrict its access to the most advanced equipment.
That technology edge was validated in a way few Chinese challengers can claim: Samsung Electronics, the world's largest NAND maker, licensed YMTC's Xtacking patents in February 2025.”
This technology edge is backed by a broad R&D base: YMTC's cumulative R&D spend reached RMB 14.2 billion between 2023 and 2025, more than 5% of revenue, with 4,796 R&D staff, over 30% of its headcount, and 5,611 granted invention patents, according to YMTC's IPO prospectus reviewed by Counterpoint Research.
Extending Xtacking Into DRAM
YMTC's next bet is to carry its Xtacking advantage beyond NAND into DRAM, a market it has never mass-produced at scale. Since October 2025, YMTC has been conducting R&D and testing of its second-generation 16Gb LPDDR5 chip (7,500 MT/s) at Fab 2, at roughly 5,000 wafers per month, without adopting High-K Metal Gate (HKMG) technology. At the same time, the company is now developing a faster, 9,600 MT/s version built on a Vertical Channel Transistor (VCT) 4F2 cell architecture, a more fundamental redesign that, if it clears performance targets, is slated for mass production at Fab 3.
Mr. Shah added, “Longer term, YMTC's roadmap points toward 3D DRAM, where cells are stacked vertically rather than laid out flat, a transition Counterpoint Research expects to favour companies like YMTC with proven wafer-bonding expertise.”
Four Vectors Counterpoint Will Be Tracking
- DRAM execution: Whether YMTC's VCT/4F² LPDDR5 (targeting 9,600 MT/s) completes qualification and reaches mass production at Fab 3 as planned, and how its 3D DRAM roadmap progresses. The earlier 7,500 MT/s LPDDR5 Gen 2 remains in R&D and testing at Fab 2, with no plans for mass production.
- Enterprise SSD traction beyond China: server revenue is already tracking from near-zero in 2024 toward an estimated 39% of total revenue by 2028; whether that controller ecosystem and the Huawei relationship convert into design wins with customers outside China, not just domestic hyperscalers.
- Export-control escalation: YMTC has been on the US Entity List since December 2022; a pending US bill, the MATCH Act, specifically names YMTC and targets the deep ultraviolet (DUV) lithography, etch and deposition tools its roadmap depends on.
- Capacity build-out: progress toward YMTC's stated long-term target of roughly 500,000 wafers per month (including DRAM) and a 20% share of the global NAND market, up from its current 16.5% shipment share.
About Counterpoint Research
Counterpoint Research is a global market research firm specializing in products across the technology ecosystem. We advise a diverse range of clients – from smartphone OEMs to chipmakers and channel players to Big Tech – through our offices located in the world's major innovation hubs, manufacturing clusters and commercial centers. Our analyst team, led by seasoned experts, engages with stakeholders across the enterprise – from the C-suite to professionals in strategy, analyst relations (AR), market intelligence (MI), business intelligence (BI), product and marketing – to deliver services spanning market data, industry thought leadership and consulting. Our core areas of coverage include AI, Automotive, Consumer Electronics, Displays, eSIM, IoT, Location Platforms, Macroeconomics, Manufacturing, Networks and Infrastructure, Semiconductors, Smartphones and Wearables. Visit our Insights page to explore our publicly available market data, insights and thought leadership, and to understand our focus, meet our analysts and start a conversation.
Follow Counterpoint Research
