

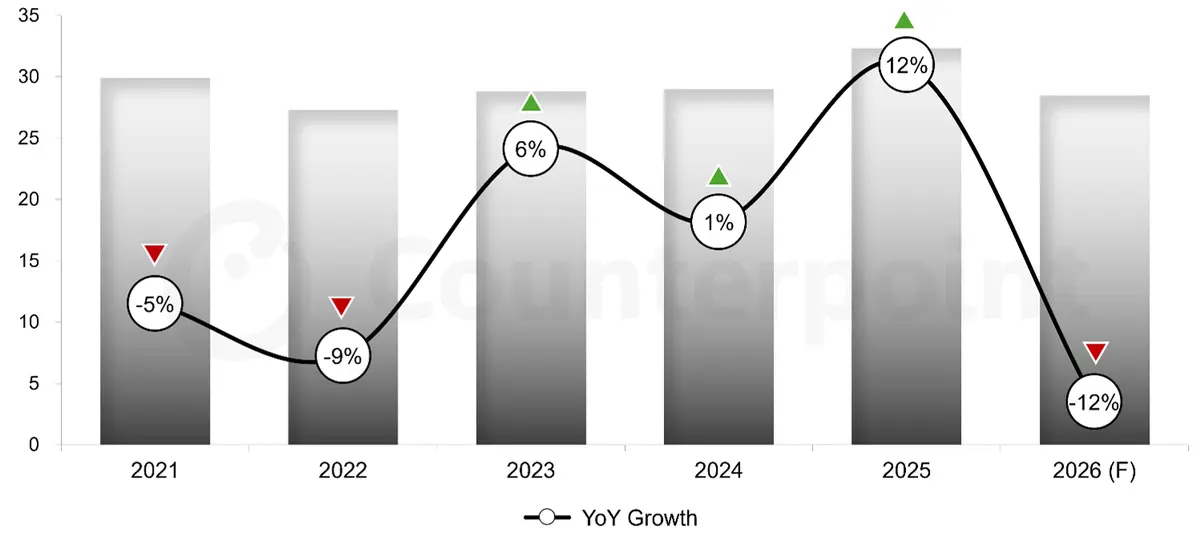
- Festival season smartphone volumes in India are expected to decline 12% YoY, hit by higher memory costs and device prices.
- Market value is expected to grow 5% YoY, supported by higher ASPs and consumers continuing to spend selectively on higher-value smartphones through financing and trade-ins.
- Consumers looking to upgrade may find the festive period an attractive buying window, as prices could rise further as component costs continue to increase.
- Mainline channel footfalls are expected to pick up during the festive season, but conversion will depend heavily on the attractiveness of financing, trade-ins and promotional offers.
New Delhi, Beijing, Berlin, Buenos Aires, Fort Collins, Hong Kong, London, Seoul, Taipei, Tokyo – Oct 6, 2026
Festive Season Smartphone Sales (in Mn Units)
Source: Counterpoint Research
Note: India festive season in 2026 = October 8 to November 8 (Expected)
India’s smartphone market is entering the key festive sales season under challenging conditions. Counterpoint Research expects smartphone volumes during the 2026 festive period to decline around 12% YoY, as elevated memory costs continue to push device prices higher, weigh on consumer demand and lead to longer replacement cycles. Despite the volume decline, market value is expected to grow 5% YoY, supported not only by higher average selling prices (ASPs), but also by consumers continuing to spend selectively on higher-value smartphones through financing, trade-ins and other affordability-led options.
Research Director Tarun Pathak said, “The key challenge this festive season will be the size of the active consumer pool. Higher smartphone prices are likely to keep many consumers on the sidelines, with discretionary upgrades being deferred and purchases increasingly driven by replacement needs. At the same time, consumers who are already planning to purchase a new smartphone may find the festive season a relatively attractive buying window, as continued increases in memory costs could lead to further price hikes. We expect consumers to be more selective and look for the right combination of financing, trade-in benefits and value, rather than upgrading simply because of festive discounts. This will make the festive season more competitive for brands, as they will be competing for a smaller pool of active buyers.”
The festive season typically accounts for a significant share of India’s annual smartphone sales. However, this year’s season comes amid sharp increases in memory costs, particularly DRAM and NAND, which have resulted in multiple rounds of smartphone price hikes. With cost pressures limiting OEMs’ ability to offer deep discounts, the festive season is likely to be shaped less by aggressive price cuts and more by affordability-led strategies, including financing, trade-ins, optimized product mixes and value-focused offerings. Consumer activity is expected to pick up across both online and mainline channels during the festive season, with mainline retail likely to see stronger footfalls. However, conversion across channels will remain highly dependent on offers, with financing, trade-in and targeted offers playing a key role.
The market is likely to become more value-conscious and selective, with consumers prioritizing devices that offer better specifications, longevity and value for money. Purchases are expected to be concentrated among replacement-driven consumers and those responding to attractive financing or promotional offers. Overall, the festive season is shaping up to be value-led rather than volume-led, with higher ASPs supporting market value growth even as cautious spending and longer replacement cycles weigh on unit sales.
About Counterpoint Research
Counterpoint Research is a global market research firm specializing in products across the technology ecosystem. We advise a diverse range of clients – from smartphone OEMs to chipmakers and channel players to Big Tech – through our offices located in the world's major innovation hubs, manufacturing clusters and commercial centers. Our analyst team, led by seasoned experts, engages with stakeholders across the enterprise – from the C-suite to professionals in strategy, analyst relations (AR), market intelligence (MI), business intelligence (BI), product and marketing – to deliver services spanning market data, industry thought leadership and consulting. Our core areas of coverage include AI, Automotive, Consumer Electronics, Displays, eSIM, IoT, Location Platforms, Macroeconomics, Manufacturing, Networks and Infrastructure, Semiconductors, Smartphones and Wearables. Visit our Insights page to explore our publicly available market data, insights and thought leadership, and to understand our focus, meet our analysts and start a conversation.
Follow Counterpoint Research

