Three of the four publicly traded flat panel display makers issued their first half Interim Reports on August 31, the date specified by Chinese securities regulations. HKC missed the deadline and, as of September 4, had not completed what would be its first Interim Report as a publicly traded company after its IPO in the first half.
The three companies that released earnings reports share a common thread – all three generate most of their revenue from LCD panels, and especially from LCD TV panels. It is no coincidence that, unlike their compatriots who focus on OLED and smaller displays, these three companies have remained consistently profitable in recent years, and that continued through the first half of 2026.
BOE Technologies
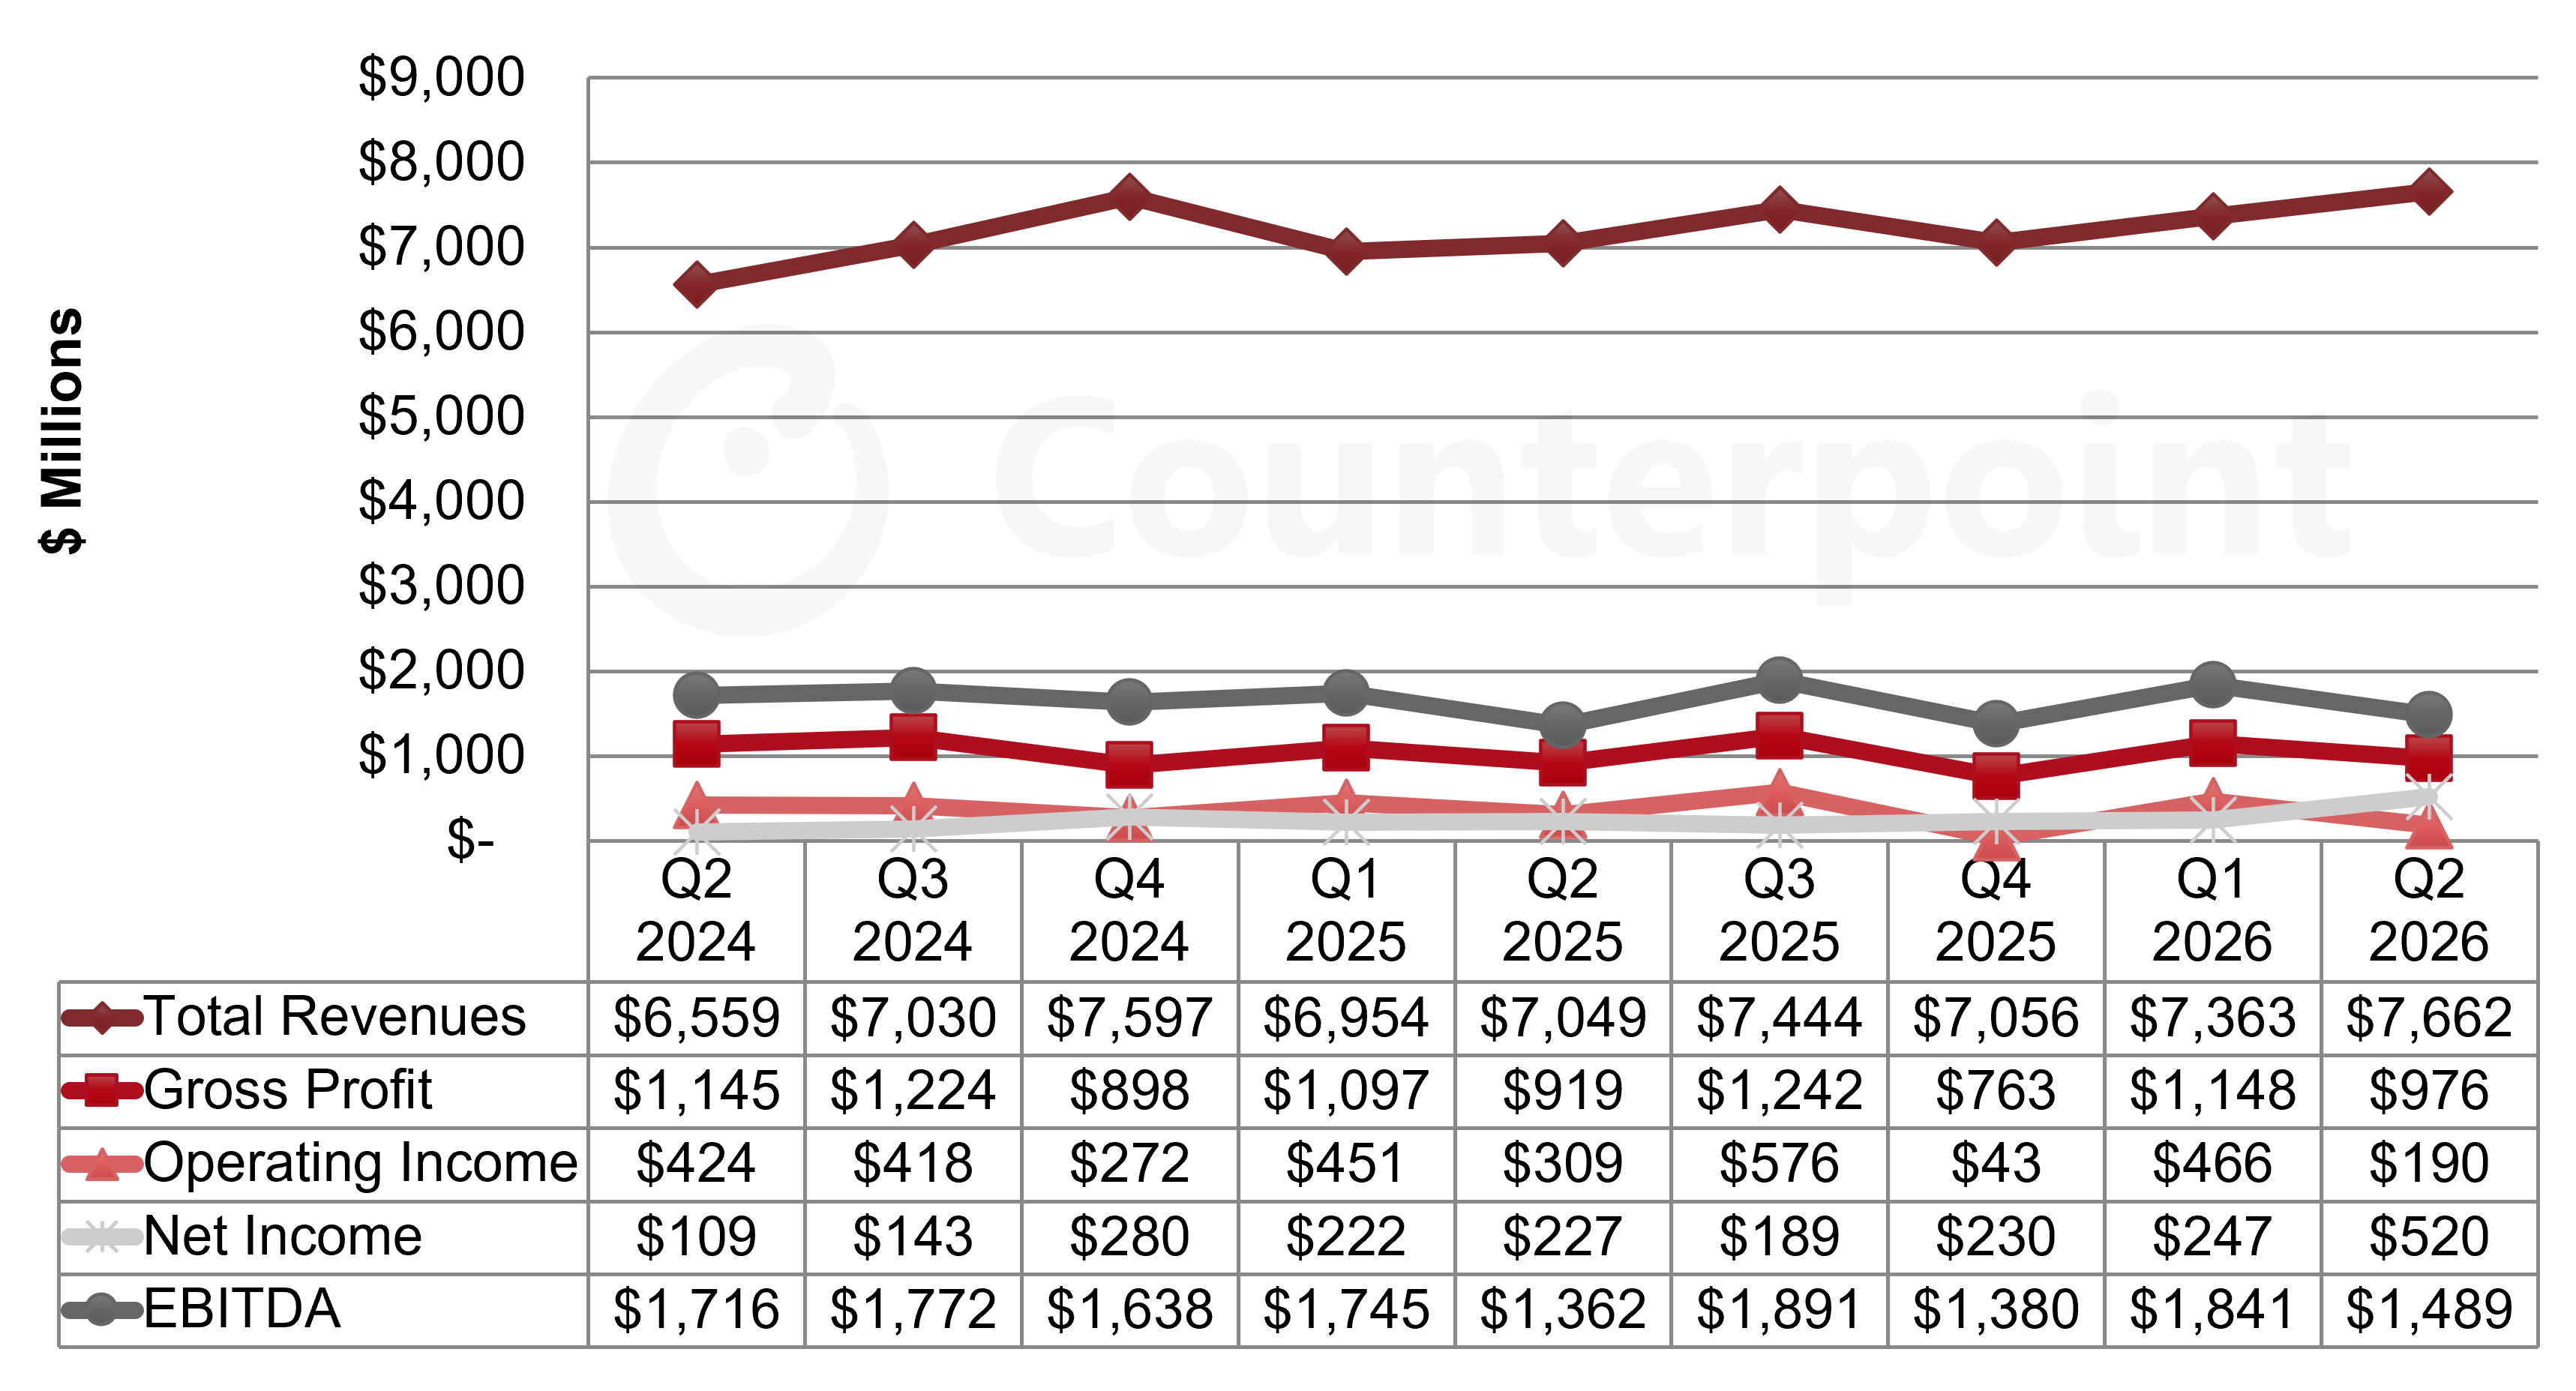
BOE reported a net profit of CNY 3.5 billion ($520 million) on revenues of CNY 52.1 billion ($7.7 billion). Revenues were up 4% QoQ and 9% YoY. BOE net income beat consensus analyst expectations of CNY 2.0 billion and revenue beat consensus expectations of CNY 50.1 billion.
BOE reported an operating profit of CNY 1.3 billion ($190 million), compared to an operating profit of CNY 3.2 billion in Q1 2026 and an operating profit of CNY 2.2 billion in Q3 2025. The company’s operating profit fell short of consensus expectations of a profit of CNY 2.7 billion.
EBITDA was CNY 10.1 billion, down 19% QoQ but up 9% YoY and falling short of consensus expectations of CNY 12.7 billion. BOE reported CNY 1.8 billion in “Other” income, including CNY 1.5 billion in profits from non-consolidated subsidiaries, CNY 2.4 billion in profit from financial assets and CNY 800 million in government subsidies unrelated to BOE's core business.
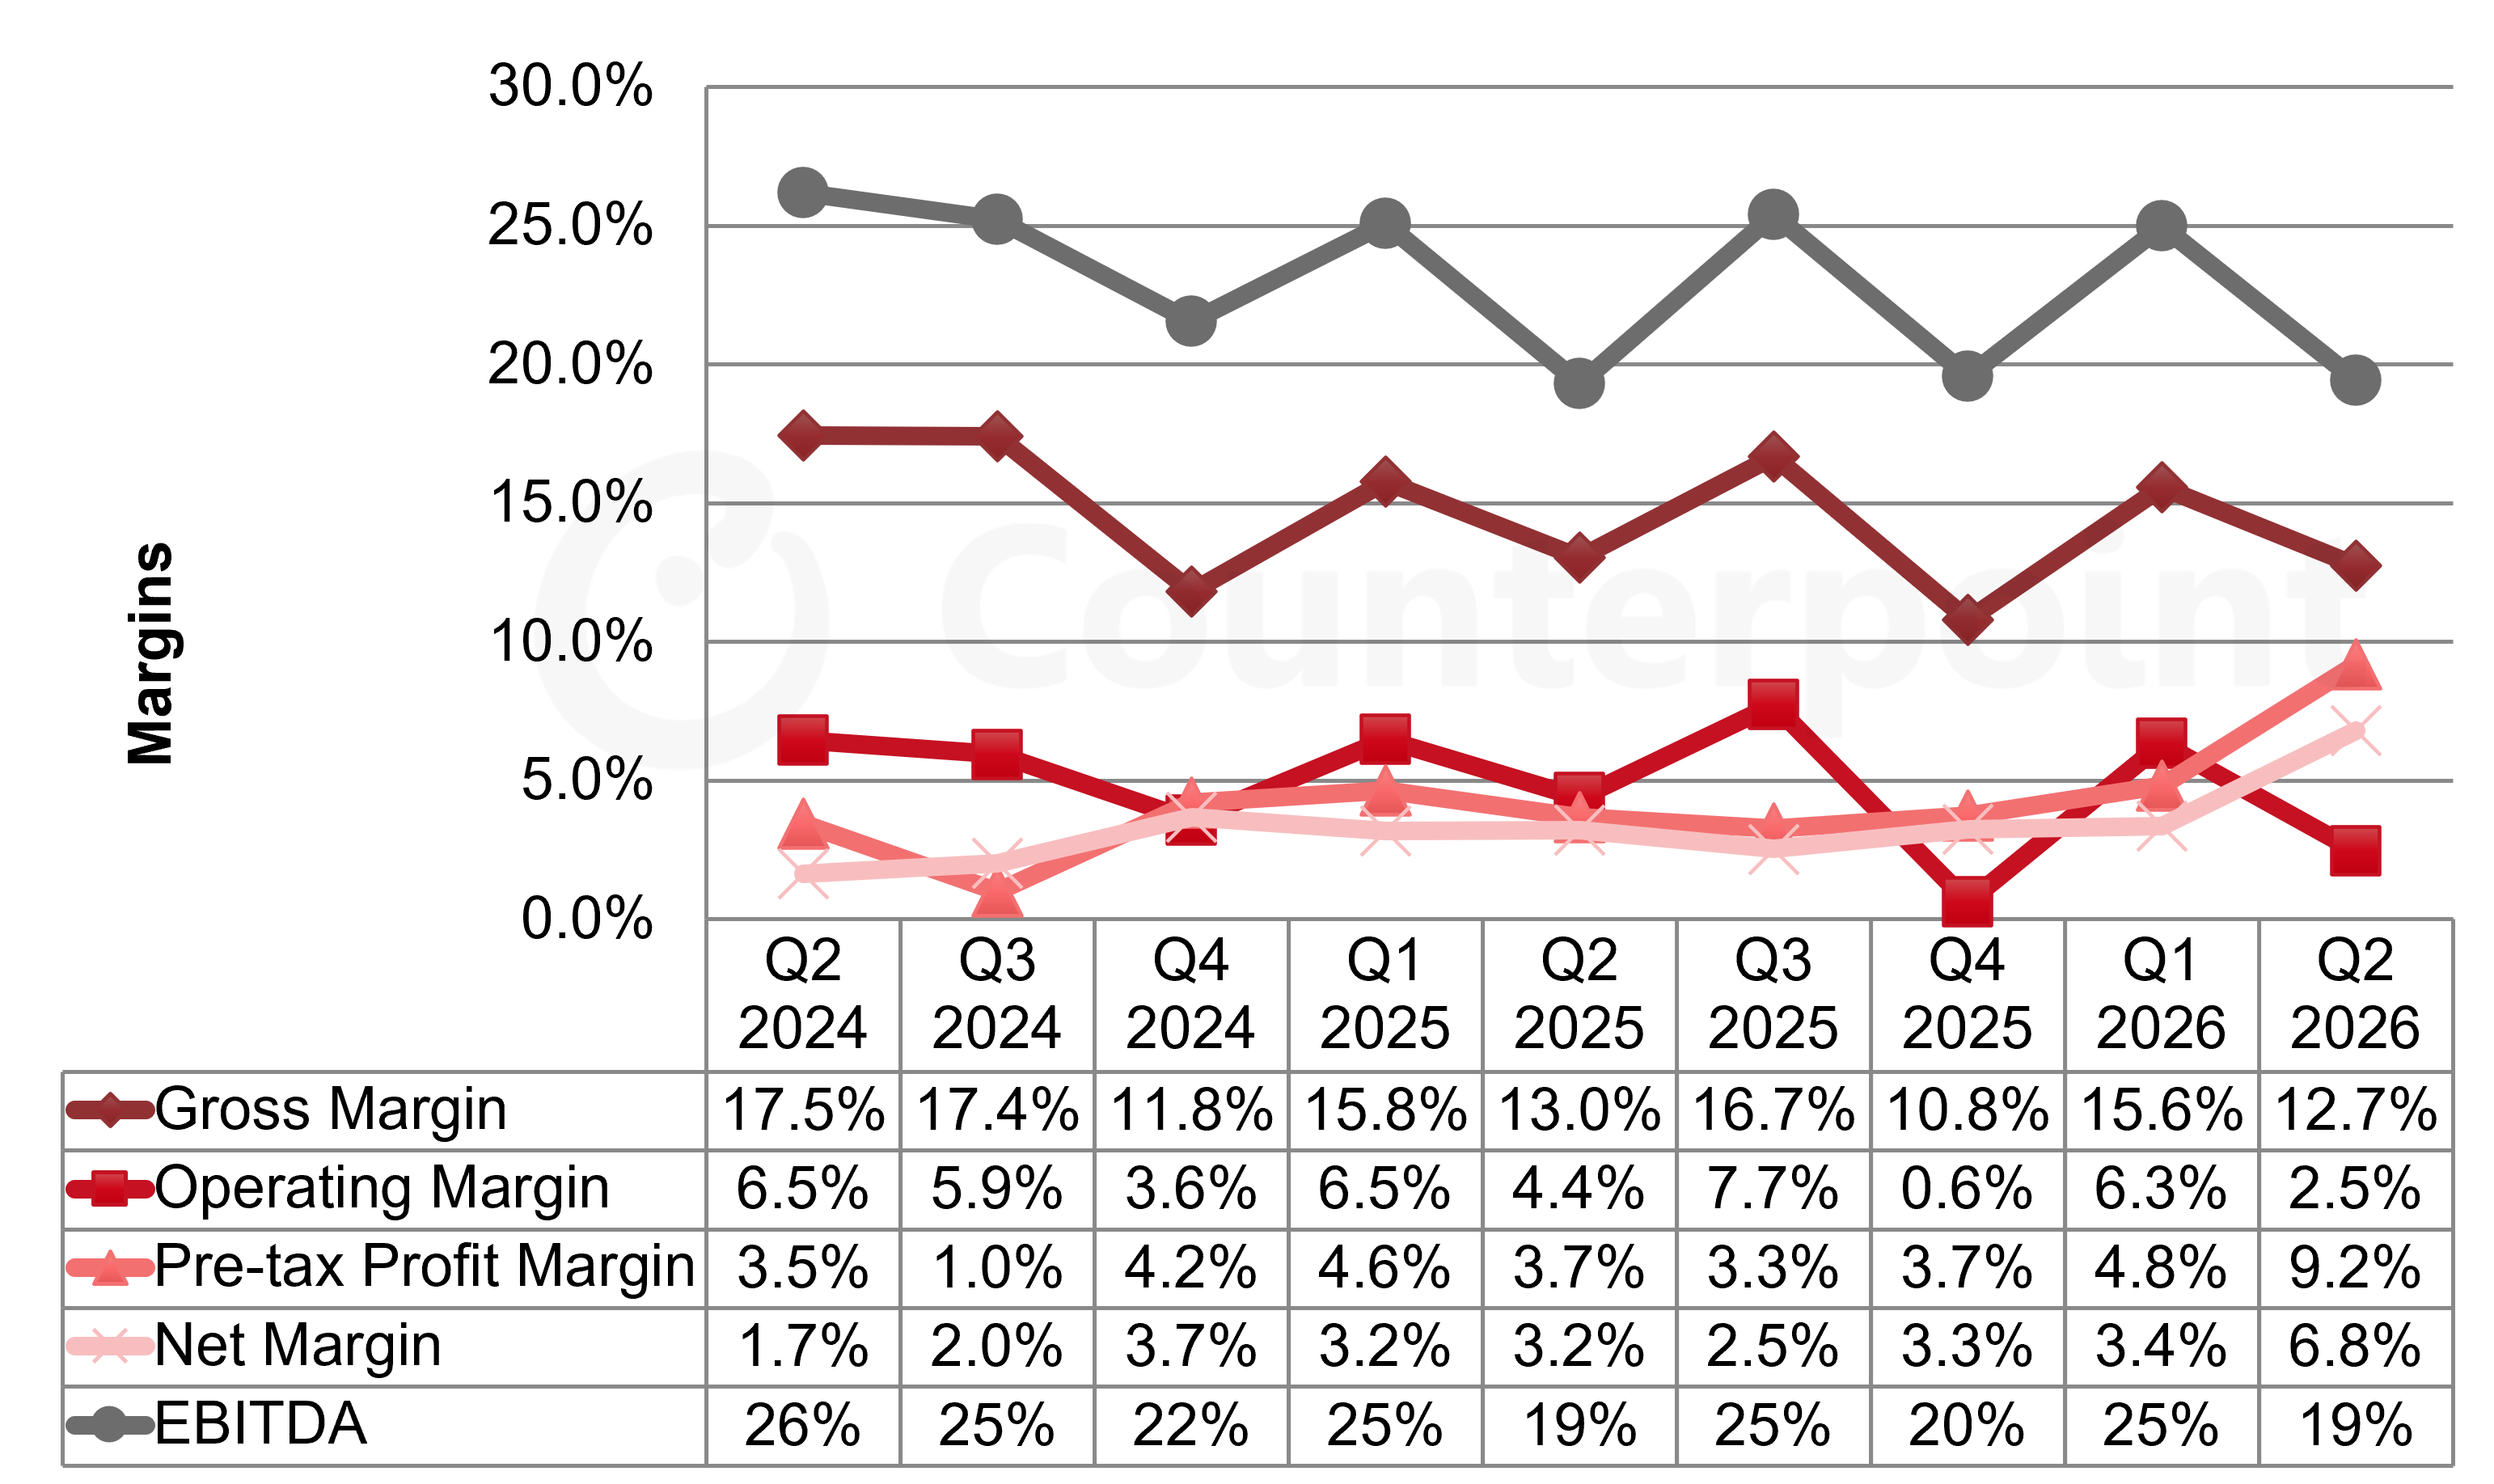
Corporate net margin increased QoQ from 3.4% to 6.8%, but gross, operating and EBITDA margins all worsened by 3%-6% QoQ.
BOE Quarterly Income Statement HighlightsSource: Counterpoint Research Quarterly Display Supply Chain Financial Health Report
BOE reported that display revenues in H1 2026 were CNY 81.7 billion ($11.9 billion), 79.3% of total corporate revenues and down 1% YoY. Display gross margin was 13%, slightly below the corporate gross margin.
BOE inventory increased by 7% QoQ, but inventory days held steady QoQ at 54. BOE continues to hold a substantial cash reserve, and cash increased 2% QoQ and 20% YoY to CNY 78 billion ($11.5 billion). BOE debt decreased 2% QoQ to CNY 142 billion, while equity decreased by 1% QoQ to CNY 208 billion. Therefore, debt/equity edged down QoQ to 68%, while net debt/equity decreased from 32% to 31%.
BOE reported positive cash flow from operations of CNY 10.5 billion ($1.5 billion), down 14% QoQ but up 23% YoY. BOE’s total capital expenditure in Q2 2026 stood at CNY 5.5 billion ($811 million), a decrease of 38% QoQ and 52% YoY. BOE had positive free cash flow of CNY 4.9 billion ($725 million). It has reported positive free cash flow in 12 of the last 14 quarters.
TCL Technologies
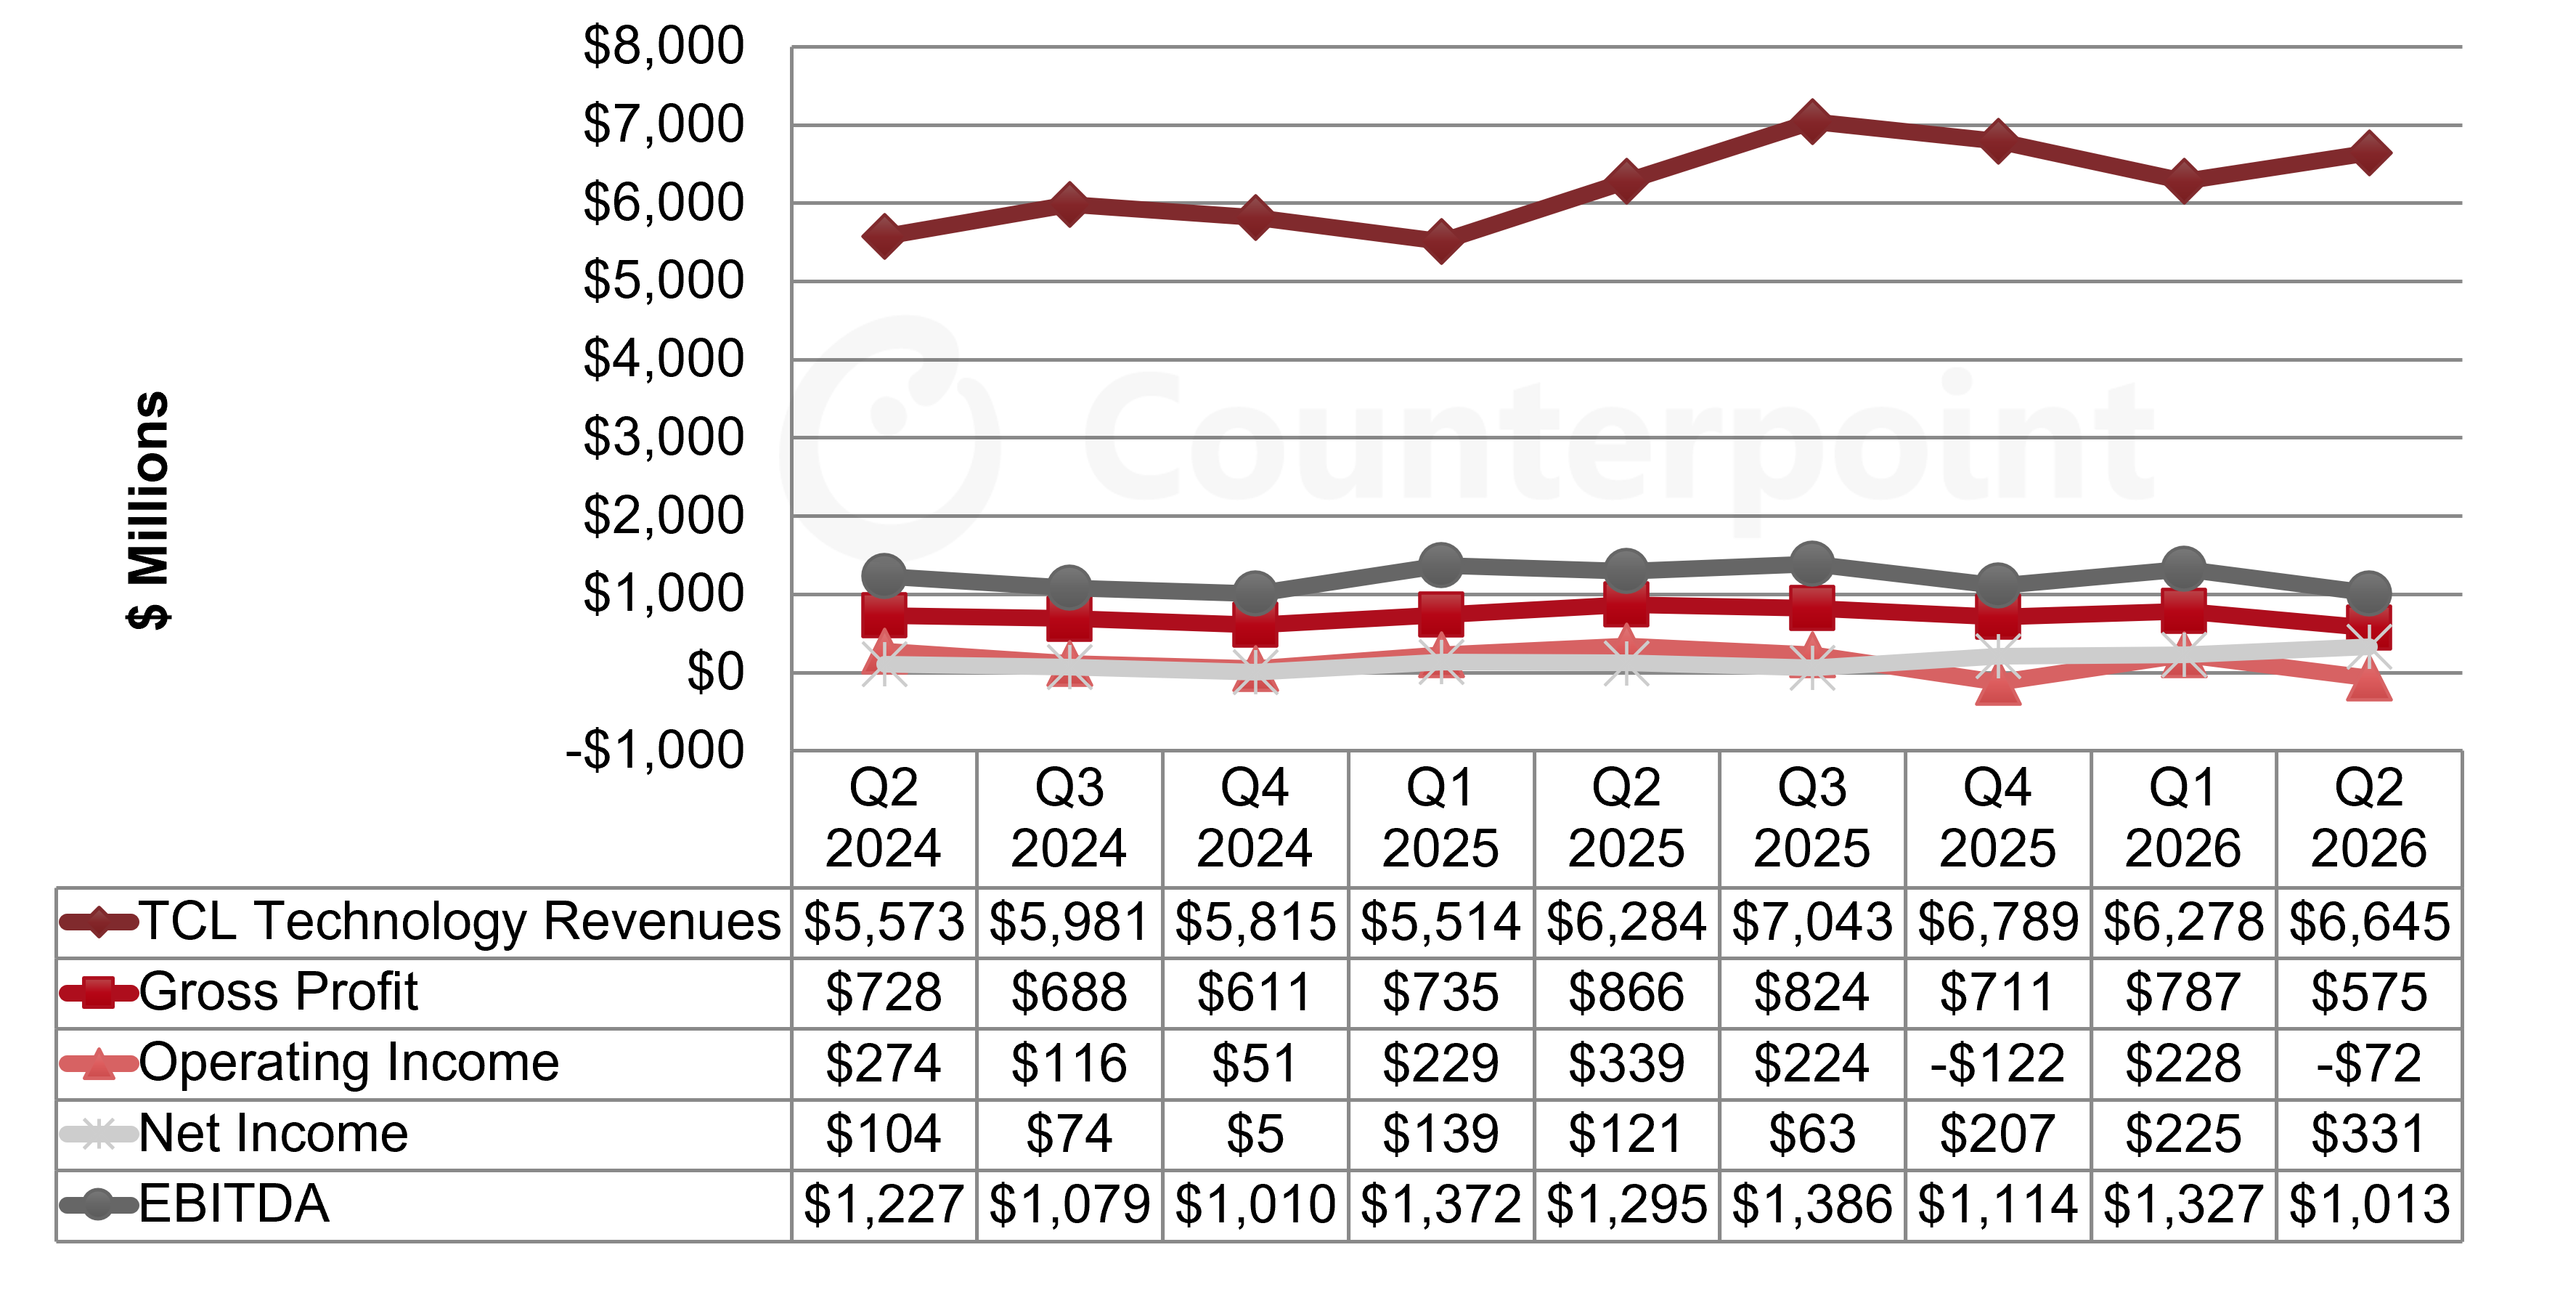
At a corporate level, TCL Technologies reported a net profit in Q2 2026 of CNY 2.25 billion ($331 million) on revenues of CNY 45.2 billion ($6.6 billion). Net income beat consensus expectations of CNY 2.00 billion, but revenues fell short of consensus expectations of CNY 49.5 billion. Revenues were up 6% QoQ and 6% YoY in $ terms. Net income was up 47% QoQ and 173% YoY.
TCL reported an operating loss of CNY 0.5 billion ($72 million), falling far short of consensus expectations of an operating profit of CNY 2.7 billion. The company reported a gain on sale of investments of CNY 893 million and a reversal of a prior asset write-down resulting in a gain of CNY 585 million. TCL EBITDA was CNY 6.9 billion ($1.0 billion) in Q2 2026, far short of consensus expectations of CNY 9.3 billion.
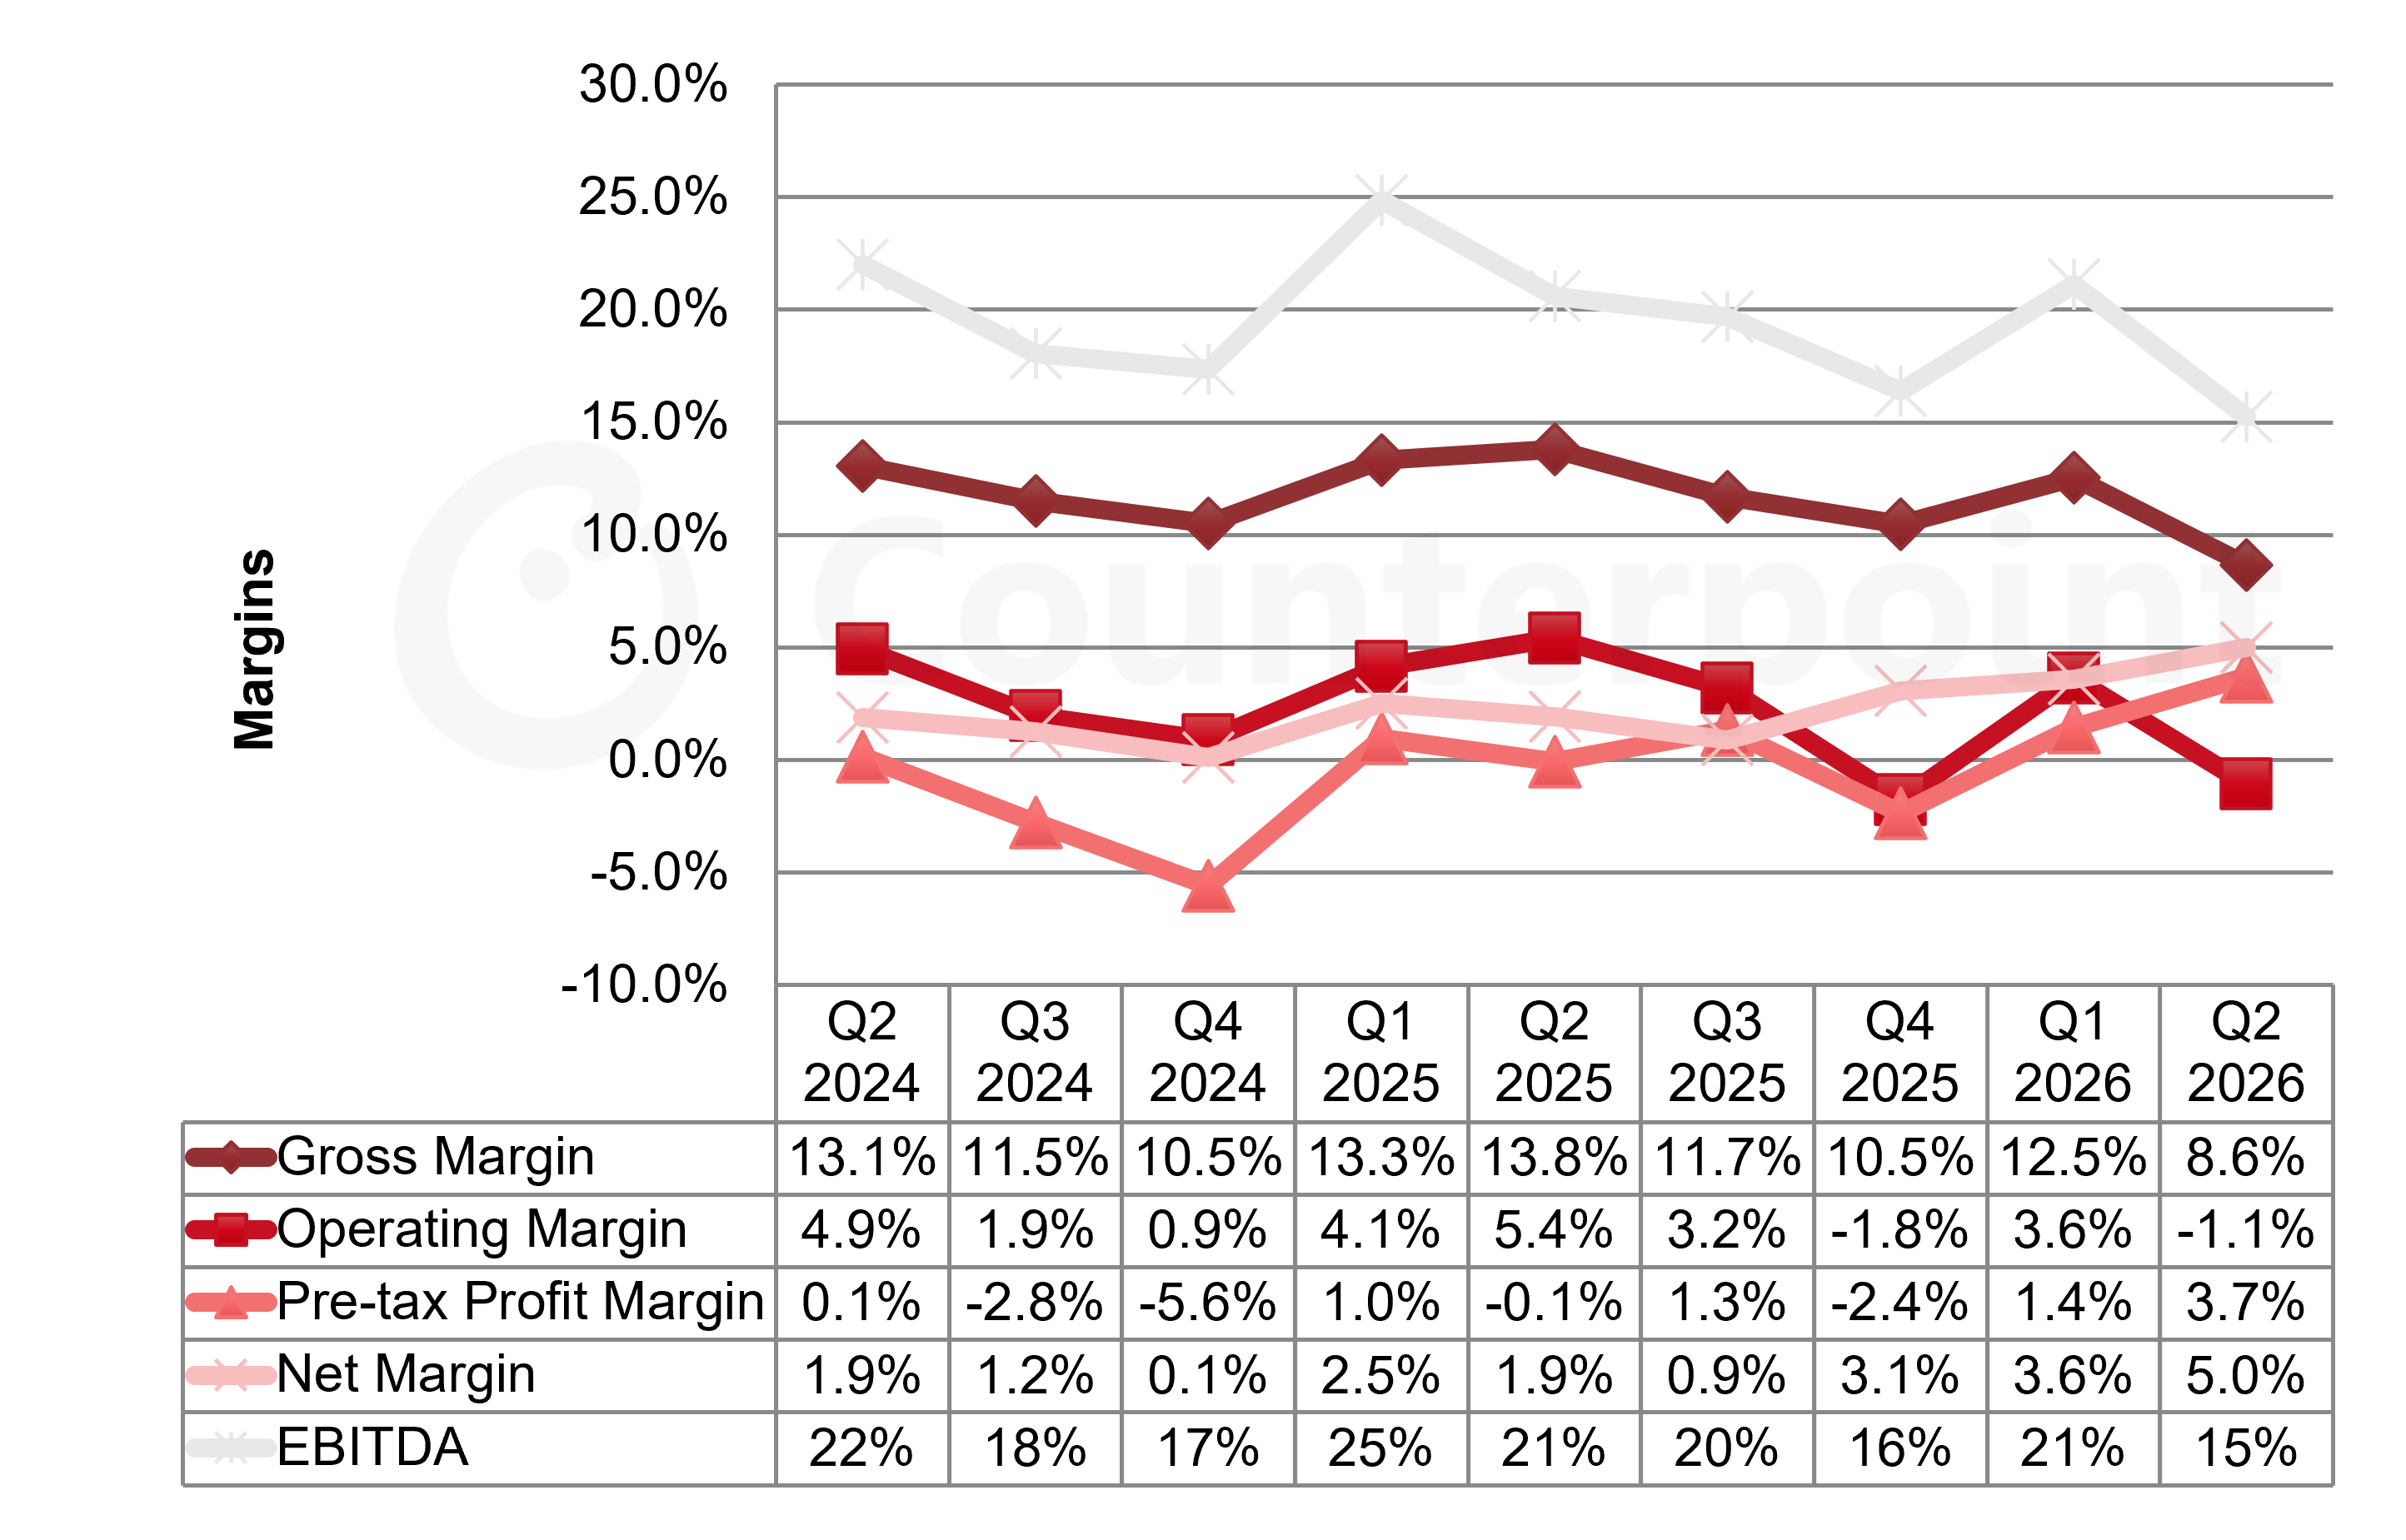
TCL gross, operating and EBITDA margins worsened by 4%-6% QoQ, but net margin improved by 1.4%.
TCL Technology Quarterly Income Statement Highlights
Source: Counterpoint Research Quarterly Display Supply Chain Financial Health Report
For H1 2026, TCL reported that display revenues from CSOT represented 64% of the corporate total. The display segment had a gross margin of 20% and net income of CNY 3.9 billion for a net margin of 7%. TCL's other main business is photovoltaic and semiconductor materials, which had a gross margin of -10%.
TCL inventory increased 13% QoQ and inventory days increased from 49 to 51. TCL debt decreased 7% or CNY 9 billion QoQ, while equity increased by 1% QoQ. Debt/equity decreased from 137% to 127% and net debt/equity decreased from 100% to 95%.
TCL reported cash flow from operations of CNY 6.23 billion ($916 million) and free cash flow of CNY 660 million ($97 million). The company has reported 12 consecutive quarters of positive free cash flow, but this was the smallest amount since Q2 2024. TCL depreciation in Q2 2026 was CNY 7.9 billion ($1.10 billion), and Q2 2026 capital expenditure was CNY 5.6 billion ($819 million).
Caihong Display Devices (CHOT)
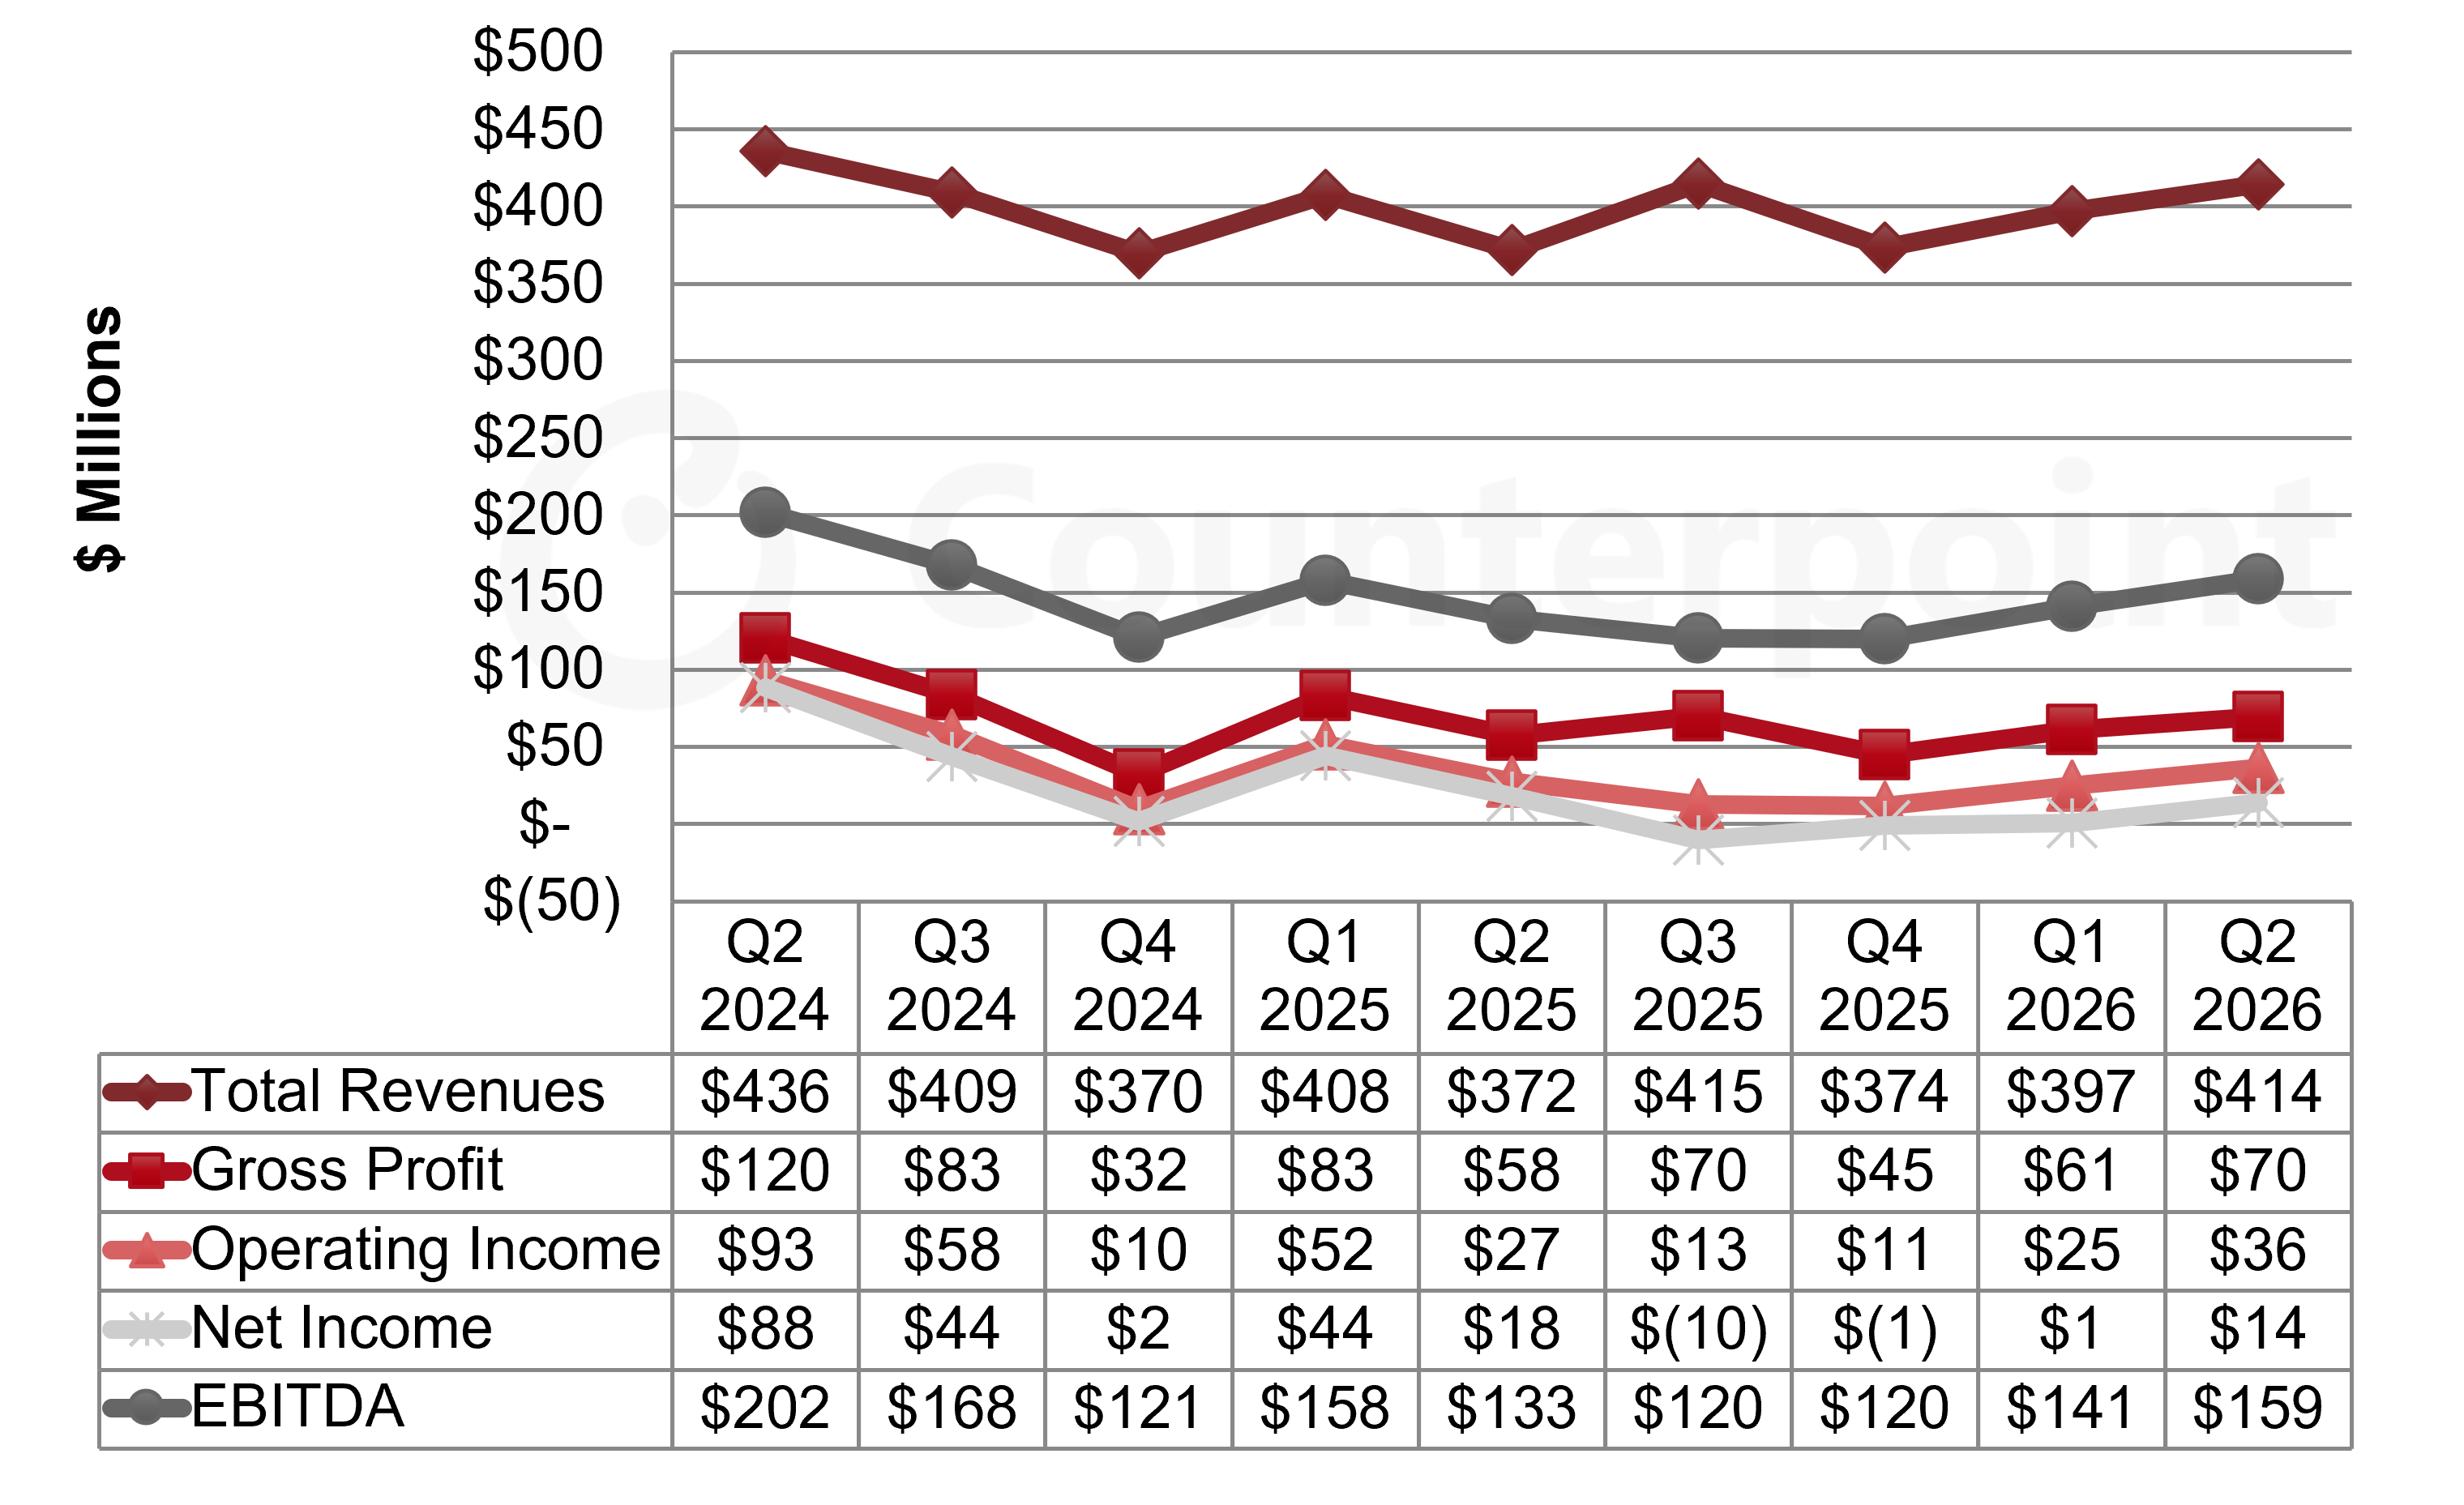
Caihong Display reported a net profit of CNY 94 million ($14 million) on revenues of CNY 2.82 billion ($414 million). Revenues were up 4% QoQ and 11% YoY. Caihong has reported net profits in 11 of the last 13 quarters.
Caihong reported an operating profit of CNY 247 million ($36 million), up 44% QoQ and 33% YoY. The company reported CNY 90 million ($13 million) in extraordinary loss.
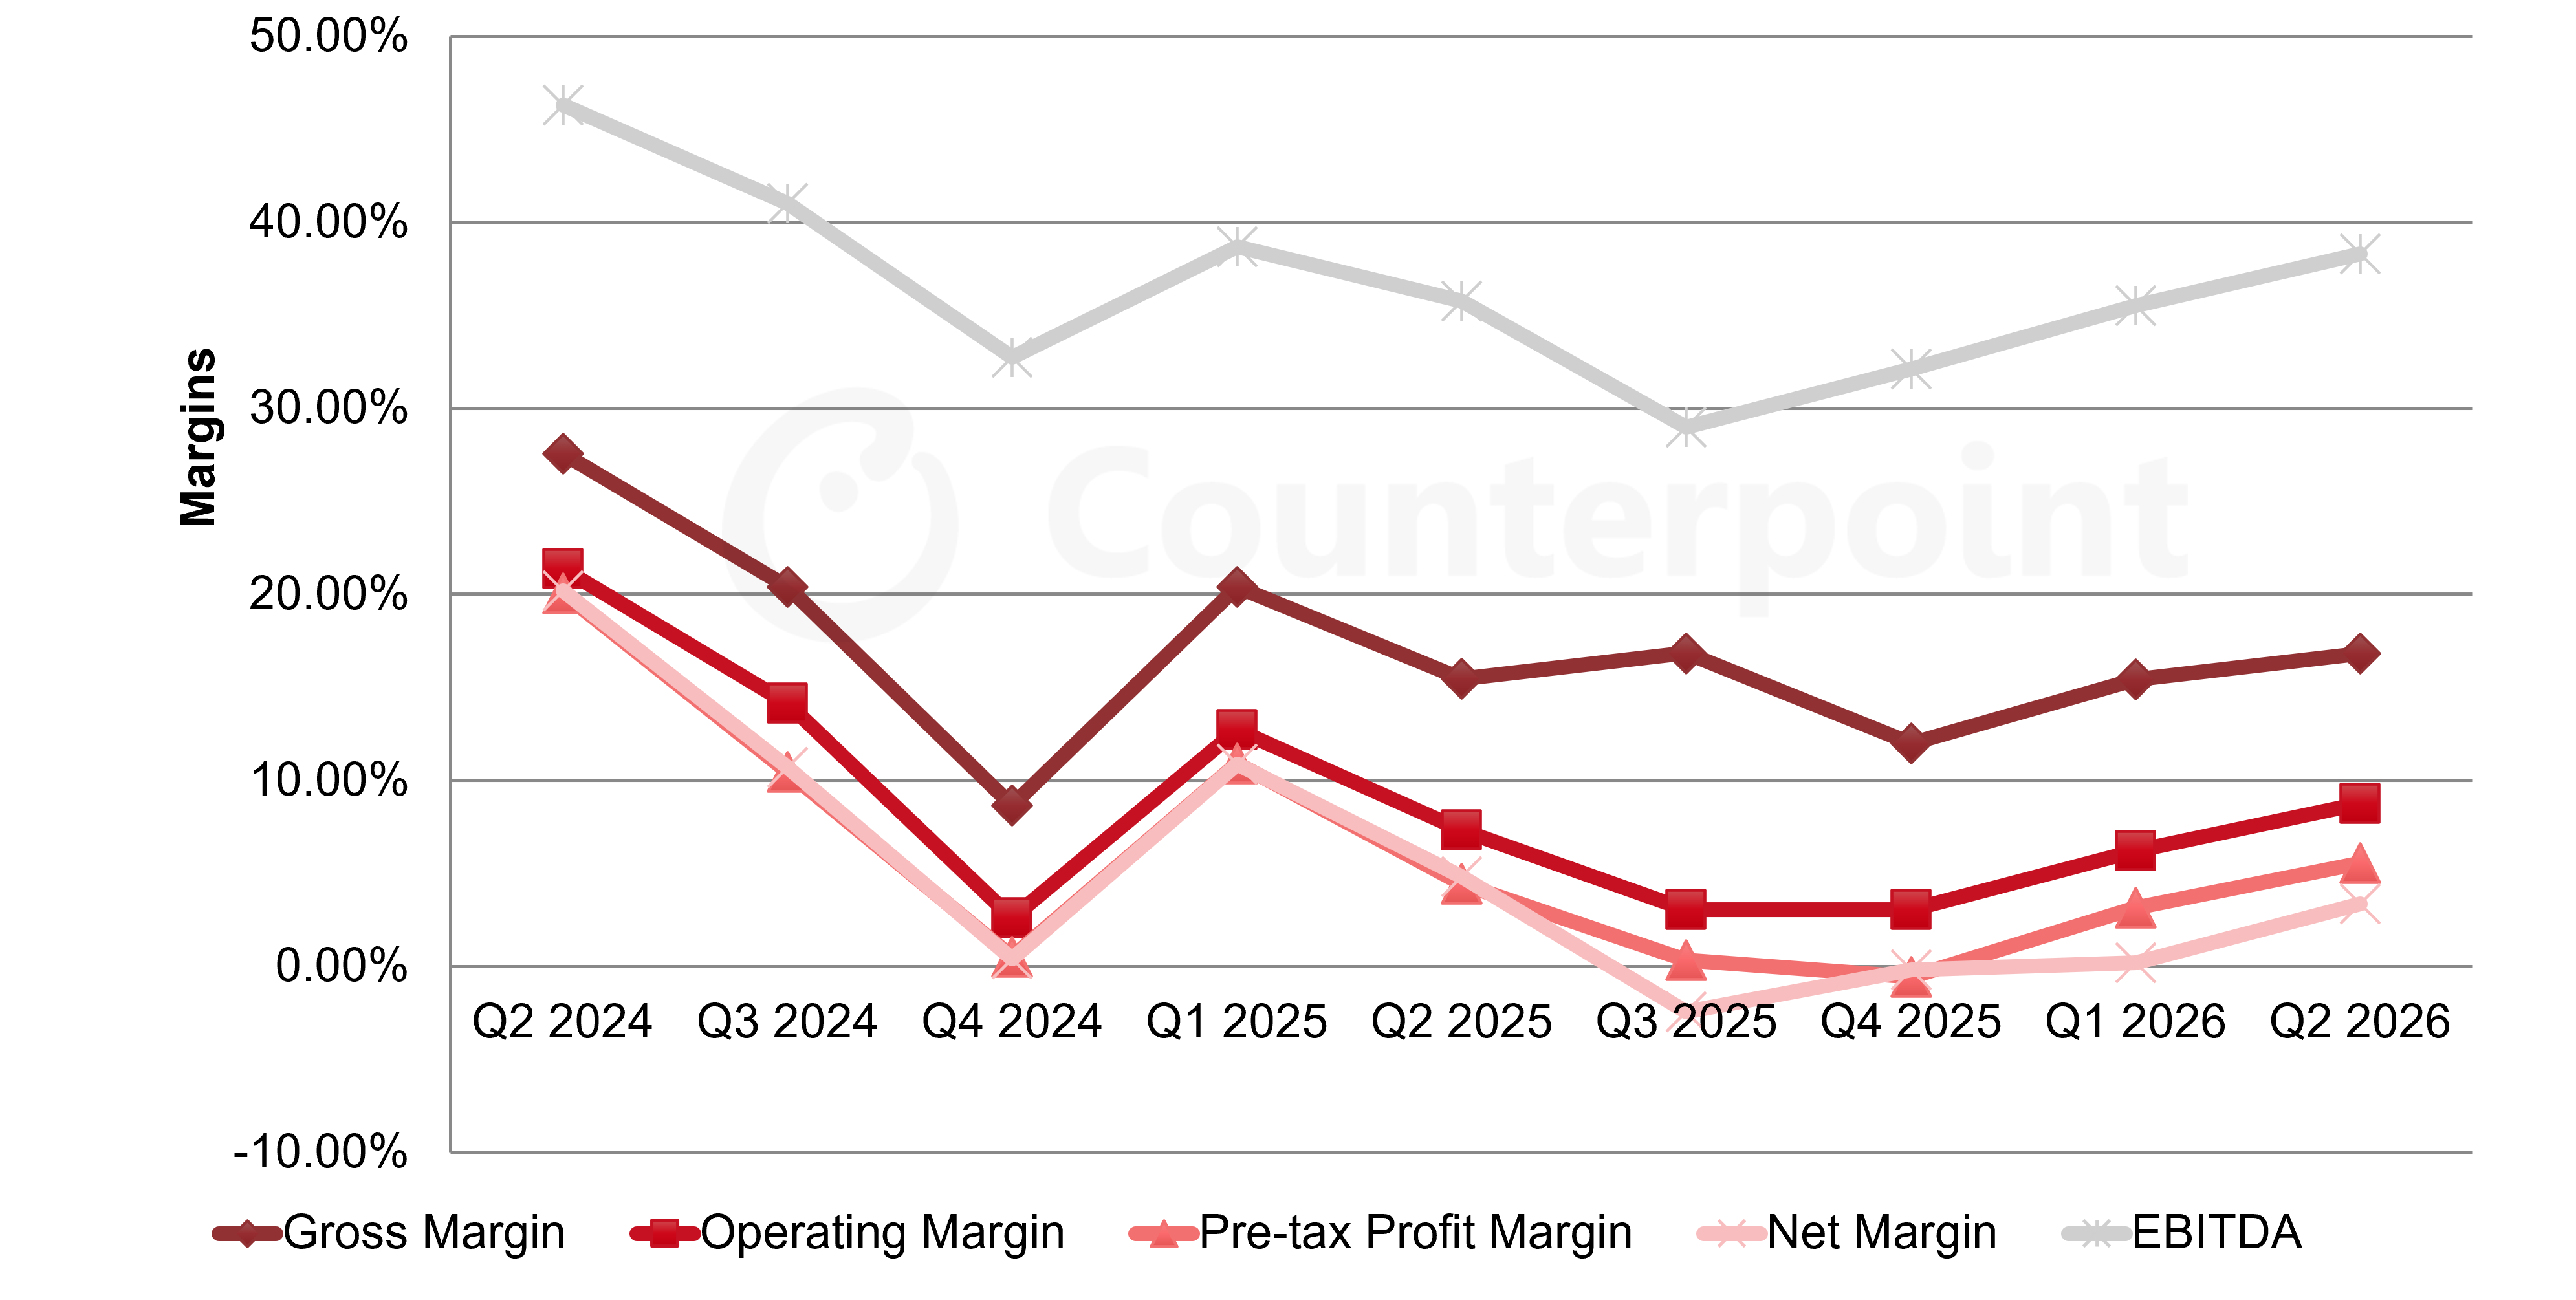
All margins improved by 1%-3%. Operating margin improved QoQ from 6.2% to 8.8%, better than 7.3% in Q2 2025. EBITDA margin increased from 35.5% in Q1 2026 to 38.3% in Q2 2026.
Caihong Display Quarterly Income Statement Highlights
Source: Counterpoint Research Quarterly Display Supply Chain Financial Health Report
In H1 2026, Caihong reported that LCD panels accounted for 87% of revenue, with the rest of the revenue attributed to glass substrates.
In Q2 2026, Inventory increased by 6% QoQ and inventory days increased from 56 to 59. CHOT debt decreased by 18% QoQ, while equity was flat QoQ. Debt/equity decreased from 41% to 34% and net debt/equity decreased from 3% to -5%.
Caihong reported depreciation expense of CNY 800 million ($118 million) in Q2 2026. Capital expenditure stood at CNY 413 million ($61 million), down 11% QoQ and 14% YoY.
In Q2 2026, Caihong reported positive cash flow from operations of CNY 1.0 billion ($146 million) and positive free cash flow of CNY 580 million ($85 million). Caihong has reported positive free cash flow in 10 of the last 12 quarters. The net FCF since Q2 2023 is CNY 3.46 billion ($488 million).
Analyst takes
These three companies represent the successful management of LCD capacity that has been implemented by Mainland Chinese FPD makers. Panel makers are managing utilization to keep LCD TV panel prices within a relatively tight range, and at the current prices, these companies are profitable. Beyond simple profitability, through steady profits and restrained capital expenditures, the companies have been generating free cash flow at an unprecedented rate in the flat panel display era.
The two larger companies, BOE and TCL Technologies, have made some efforts to diversify their businesses into new business lines. BOE’s ventures have been oriented closer to vertical integration, and taken as a group, they are profitable, but represent only 20% of corporate revenues. TCL’s foray into photovoltaics represents a larger portion of its corporate revenues but has consistently lost money in recent years as that industry remains in serious oversupply.
Caihong Display has taken the route of vertical integration by developing and growing a display glass business which, though not profitable, is at least break-even. That business may face difficulties ahead after the recent US ITC ruling that Caihong (aka Irico) made use of stolen trade secrets from Corning. Even without the display glass business, though, Caihong is a healthy, profitable firm.
Category
Industry
Display
Service
Standard
Report Type
Report
Time Period
Other
Receive our insightful weekly newsletter and stay ahead of the competition.
Author
Bob Obrien
Robert J (Bob) O’Brien joined Counterpoint Research as part of its acquisition of DSCC, where he was Co-Founder, Principal and CFO of DSCC. Bob has decades of experience turning market and business analysis into strategic insights in the display and electronics industries. At DSCC, Bob takes the lead role in analysis of display materials, including glass and AMOLED materials, and covers developments in TV and other large-screen display applications. He is the principal author of DSCC’s AMOLED Material Report, the Advanced TV Shipment Report, and the Display Glass Report, and Bob contributes regularly to the DSCC Weekly Review.