
- The US Postpaid carriers and Cable MVNOs alike will continue with bundled and value adding services to reduce churn and increase NPS scores in 2025.
- More changes to legacy plans, free line offers, and fee structures are expected to continue to drive up ARPA in postpaid.
- Upgrade rates will rebound and holding periods will begin to fall in 2025.
- Price band consolidation will occur pushing sales into the $100-$199 price band for prepaid and into the $800+ price band in postpaid as premiumization continues.
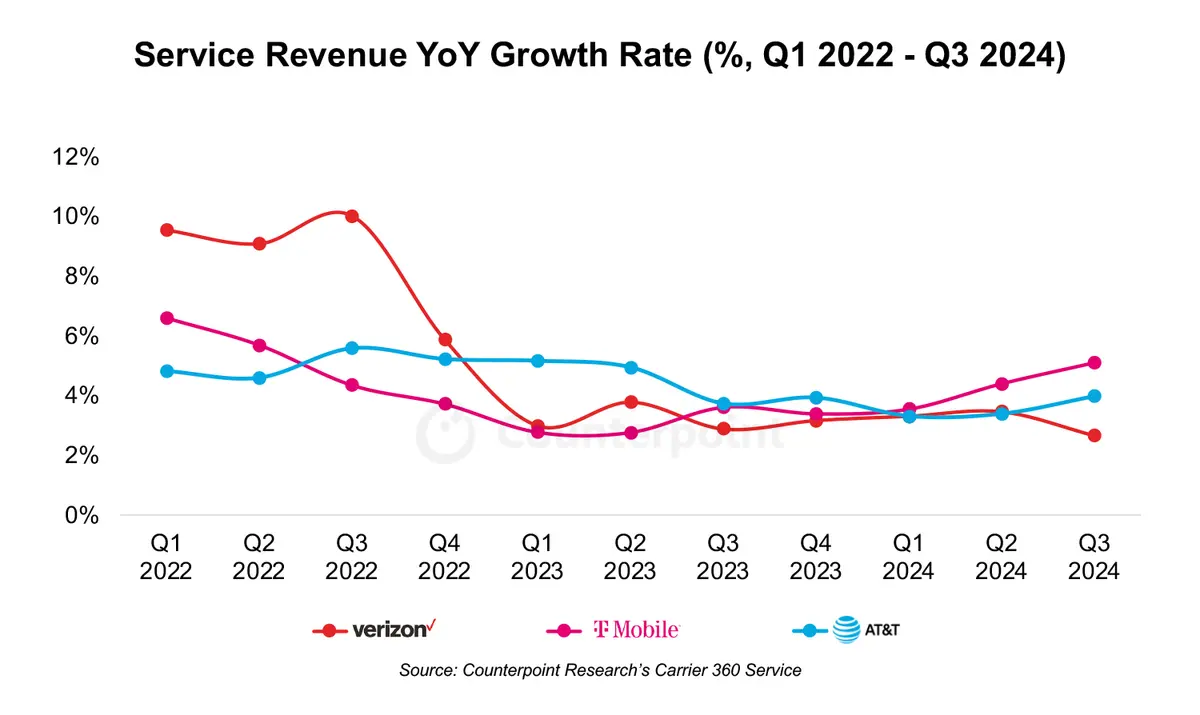
US postpaid carriers are expected to continue their efforts to reduce churn through bundling while also working to grow average revenue per account (ARPA) in 2025. The big 3 US carriers are expected to grow their broadband businesses as a key part of their bundled services strategies.
Service Revenue YoY Growth Rate (%), Q1 2022-Q3 2024
Source: Counterpoint Research’s Carrier 360 Service
Upgrade rates will likely bottom out in 2025 as holding periods are reaching their peak. This bodes well for device sales in the US in 2025. However, prepaid sales are expected to continue to decline. Prepaid consumers are also expected to continue buying down in price tiers opting for more basic functionality as they continue to feel the effects of inflationary pressures with the $100-$199 price band growing in total share of sales. On the opposite end of the spectrum, we expect to see postpaid customers continue to buy as higher income individuals remain resilient in their spending and postpaid carriers continue to heavily subsidize premium smartphones.
Cable MVNOs continue to bleed broadband subscribers and are turning to aggressive device subsidies, akin to the “Big 3,” to attract and retain wireless subscribers. 2025 is poised to promote more frequent upgrading behavior but this does not necessarily mean stronger subsidies. Carriers are leaning on value added services attached to device plans more than ever to retain customers and are saving the strongest device subsidies for only the most premium plans.
An expanded report on Counterpoint’s US Carrier expectations can be found here.