

- Pure-play foundry market grew 29% YoY in Q2, driven by surging demand for AI semiconductors
- TSMC maintained a 73% market share for two consecutive quarters, supported by 2nm mass production and 3nm expansion
- Samsung Foundry retained its second-place position, focusing on improving SF2 yields
- SMIC achieved record quarterly revenue while holding the third spot, fueled by strong domestic and international orders
According to global market research firm Counterpoint Research, the pure-play foundry market grew 29% year-on-year in the second quarter of 2026, driven by a surge in AI semiconductor-related orders and capacity reallocation. Supply-demand imbalances were observed across both advanced and mature nodes.
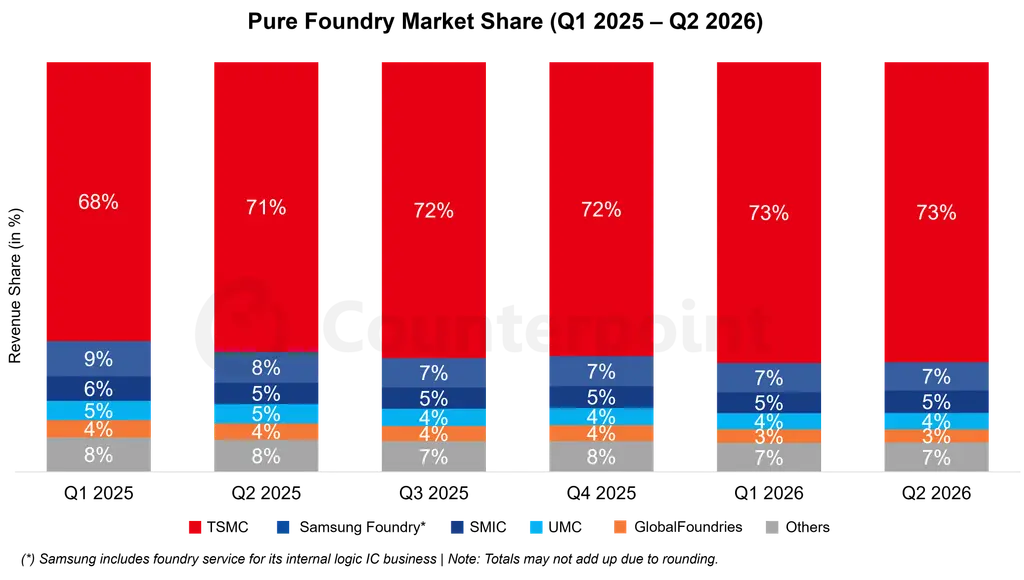
Pure-Play Foundry Market Share in Q2 2026 (Q1 2025 – Q2 2026)
| Brand | Q1 2025 | Q2 2025 | Q3 2025 | Q4 2025 | Q1 2026 | Q2 2026 |
|---|---|---|---|---|---|---|
| TSMC | 68% | 71% | 72% | 72% | 73% | 73% |
| Samsung Foundry | 9% | 8% | 7% | 7% | 7% | 7% |
| SMIC | 6% | 5% | 5% | 5% | 5% | 5% |
| UMC | 5% | 5% | 4% | 4% | 4% | 4% |
| GlobalFoundries | 4% | 4% | 4% | 4% | 3% | 3% |
| Others | 8% | 8% | 7% | 8% | 7% | 7% |
Source: Counterpoint Research Pure Foundry Market Share Tracker
TSMC maintained a 73% foundry market share for two consecutive quarters, supported by the mass production of its 2nm process, the expansion of its 3nm process, and supply shortages in 8-inch and 12-inch mature nodes and advanced packaging.
Samsung Foundry retained its second-place position, with its market share remaining largely unchanged compared to the first quarter of 2026. Samsung Foundry continues to focus on improving yields for its SF2 process, while demand for SF4 and SF5, along with foundry wafer price hikes in the first half of the year, served as key drivers for revenue growth.
SMIC maintained its third-place position, recording its highest-ever quarterly revenue in Q2 2026. The performance was driven by robust domestic demand in China and an influx of international orders that exceeded capacity.
Counterpoint Research expects that pure-play foundry utilization rates will remain relatively high in the second half of 2026, as foundry wafer average selling prices (ASP) continue to rise.
[Counterpoint Research]
Counterpoint Research is a global industry and market research firm providing market data, insights, reports, and consulting services across the technology ecosystem. We advise a diverse range of global clients across the supply chain, from semiconductor manufacturers, component suppliers, and software and application developers to telecommunications service providers, distribution channels, and investors.
Our experienced team of analysts supports clients through global offices located in major innovation hubs, manufacturing clusters, and key commercial centers worldwide. We engage continuously with C-suite executives and departments including strategy, market intelligence, supply chain, R&D, product management, marketing, and sales.
Key Research Areas of Counterpoint
: Artificial Intelligence (AI), Automotive, Cloud, Connectivity, Consumer Electronics, Displays, eSIM, IoT (Internet of Things), Location-based Platforms, Macroeconomics, Manufacturing, Networks and Infrastructure, Semiconductors, Smartphones, and Wearable Devices. To access published market data, insights, and reports, or to connect with our analysts, please visit the Counterpoint Library.


