

- Memory cost pressure is becoming long-term as AI demand shifts capacity away from legacy DRAM and flash, leading to uneven impact across technologies.
- Smart modules, 5G and RedCap are the most affected, while Cat 1 bis and NB-IoT remain relatively insulated due to lower memory requirements.
- As a result, 2026 IoT module growth is revised down to 4% YoY (from 8% estimated in Q3 2025), with slower adoption of higher-end modules.
- Near-term margin pressure may lead to a gradual shift toward better pricing discipline and higher margins.
Access to full report here: LPDDR4 Supply Constraints, Rising Memory Costs Impacting High-end Cellular IoT Modules
The impact of rising memory prices on the cellular IoT module market is becoming increasingly structural rather than cyclical. As memory vendors continue reallocating capacity toward HBM and advanced nodes to support AI workloads, legacy DDR3, DDR4 and certain flash segments are tightening. This reprioritization of wafer capacity is beginning to affect smart modules, 5G Modules and high performance IoT devices.
According to Counterpoint Research’s Cellular IoT Module Forecast, Q4 2025 report, global cellular IoT module growth in 2026 is now expected to remain broadly flat at 4% YoY, compared to the previous expectation of 8% YoY. Adoption of smart modules, 5G and 5G RedCap modules is likely to slow as memory constraints and elevated component costs weigh on deployment plans.
However, overall market volumes will continue to be supported by lower-tier segments such as Cat 1 bis and NB IoT, which are less exposed to high-density memory requirements and therefore comparatively insulated from the current pricing pressure.
Global Cellular IoT Module Shipments YoY Growth Forecast and Revisions, 2026
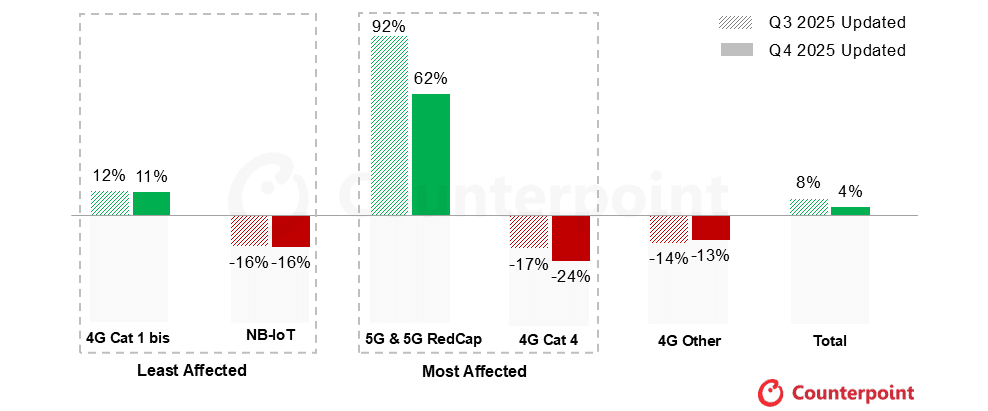
Source: Global Cellular IoT Module Forecast, Q4 2025
4G and 5G smart modules that integrate application processors and 2GB to 16GB LPDDR4 are emerging as the most exposed segment to current memory supply constraints. These modules are widely used across smart handheld terminals, Smart POS, surveillance cameras, drones, robotics, and industrial HMI panels, making them critical to a broad range of edge AI-driven applications.
As LPDDR4 supply remains tight amid increasing demand from edge AI and high-performance IoT use cases, BOM costs are expected to rise, putting sustained pressure on vendor margins unless module pricing is adjusted accordingly. However, the impact is not limited to the supply side. Rising memory prices are also beginning to affect demand at the end-device level, particularly in cost-sensitive segments where higher device prices can slow adoption and deployment.
Memory is no longer just a smartphone or data center variable. It is now a defining factor shaping the economics of 5G, RedCap and advanced IoT modules. The next 18 to 24 months will determine whether this represents temporary disruption or a structural reset in module market dynamics.


