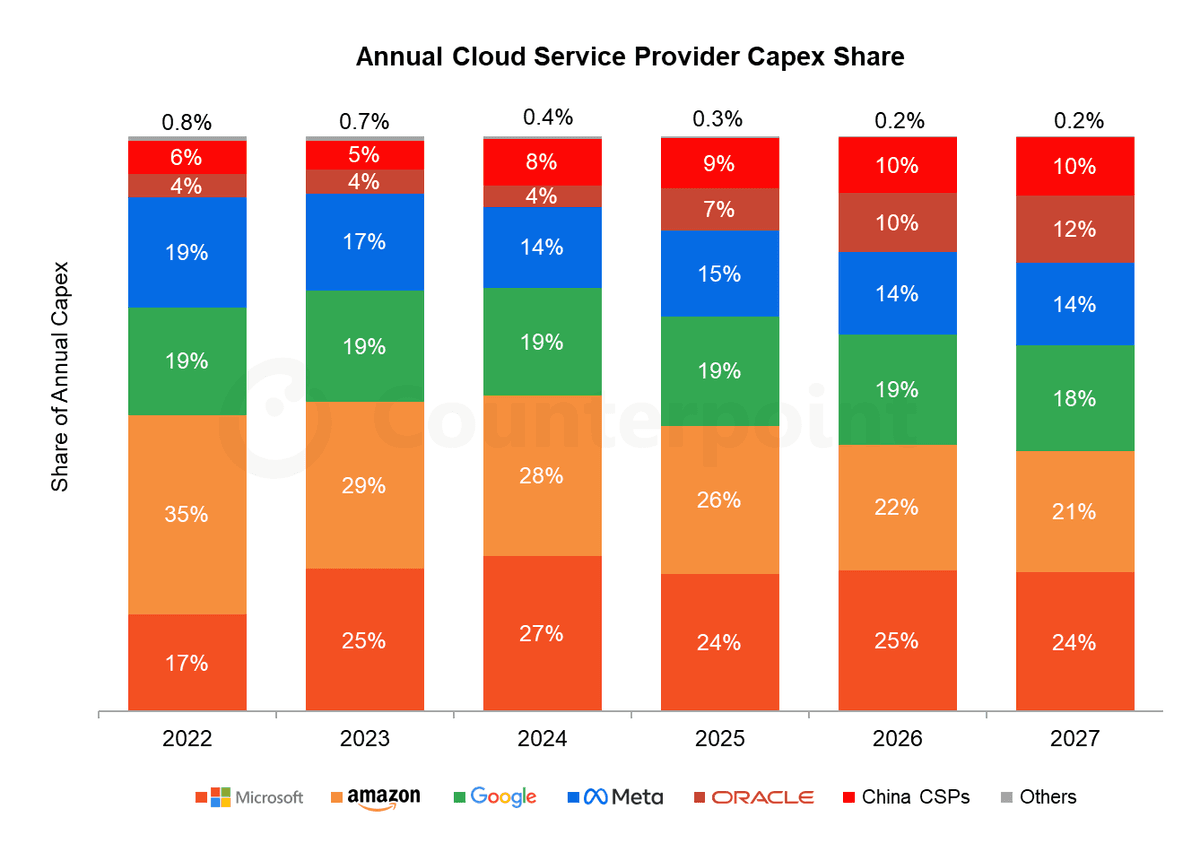
Market Highlights
- We expect CSP capex to grow at 37% CAGR from 2022 to 2027, with AI-driven spending inflection beginning 2024.
- The majority of incremental capex driven by hyperscalers, led by Microsoft and Amazon, with accelerating contributions from Google and Meta.
- Cloud service provider (CSP) capex shifts from stable mid-teens CAGR from 2019-2023 to structurally higher levels in the post GenAI era.
- This reflects a business model reset, as cloud platforms move from relative asset-light software operators to capital-intensive AI infra owners; sustained heavy investment the new baseline.
- Export controls and limited access to advanced manufacturing limiting Chinese CSP – including Alibaba, Baidu, and Tencent – capex growth, keeping global share below 10% by 2025.
- As a result, domestic players are focusing on improving LLM efficiency and software capabilities rather than scaling infrastructure.
| Annual Cloud Service Provider | 2022 | 2023 | 2024 | 2025 | 2026 | 2027 |
|---|---|---|---|---|---|---|
| Microsoft | 17% | 25% | 27% | 24% | 25% | 24% |
| Amazon | 35% | 29% | 28% | 26% | 22% | 21% |
| 19% | 19% | 19% | 19% | 19% | 18% | |
| Meta | 19% | 17% | 14% | 15% | 14% | 14% |
| Oracle | 4% | 4% | 4% | 7% | 10% | 12% |
| China CSPs | 6% | 5% | 8% | 9% | 10% | 10% |
| Others | 0.8% | 0.7% | 0.4% | 0.3% | 0.2% | 0.2% |


