
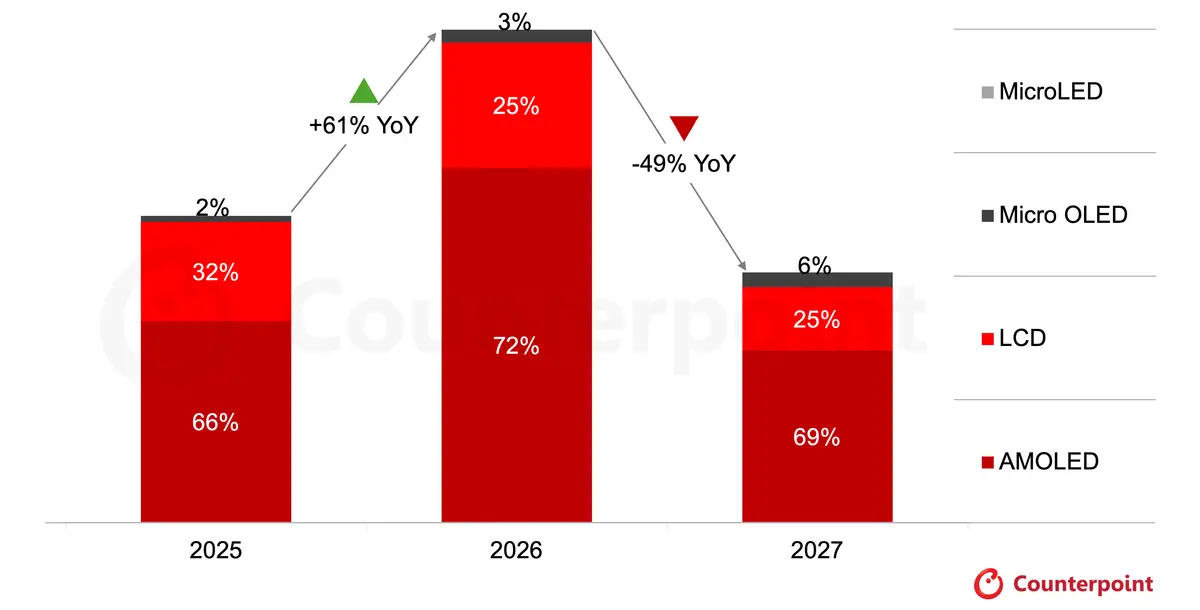
- Global display equipment capex is projected to fall 49% YoY in 2027 to $5.5 billion, after a 61% YoY surge in 2026
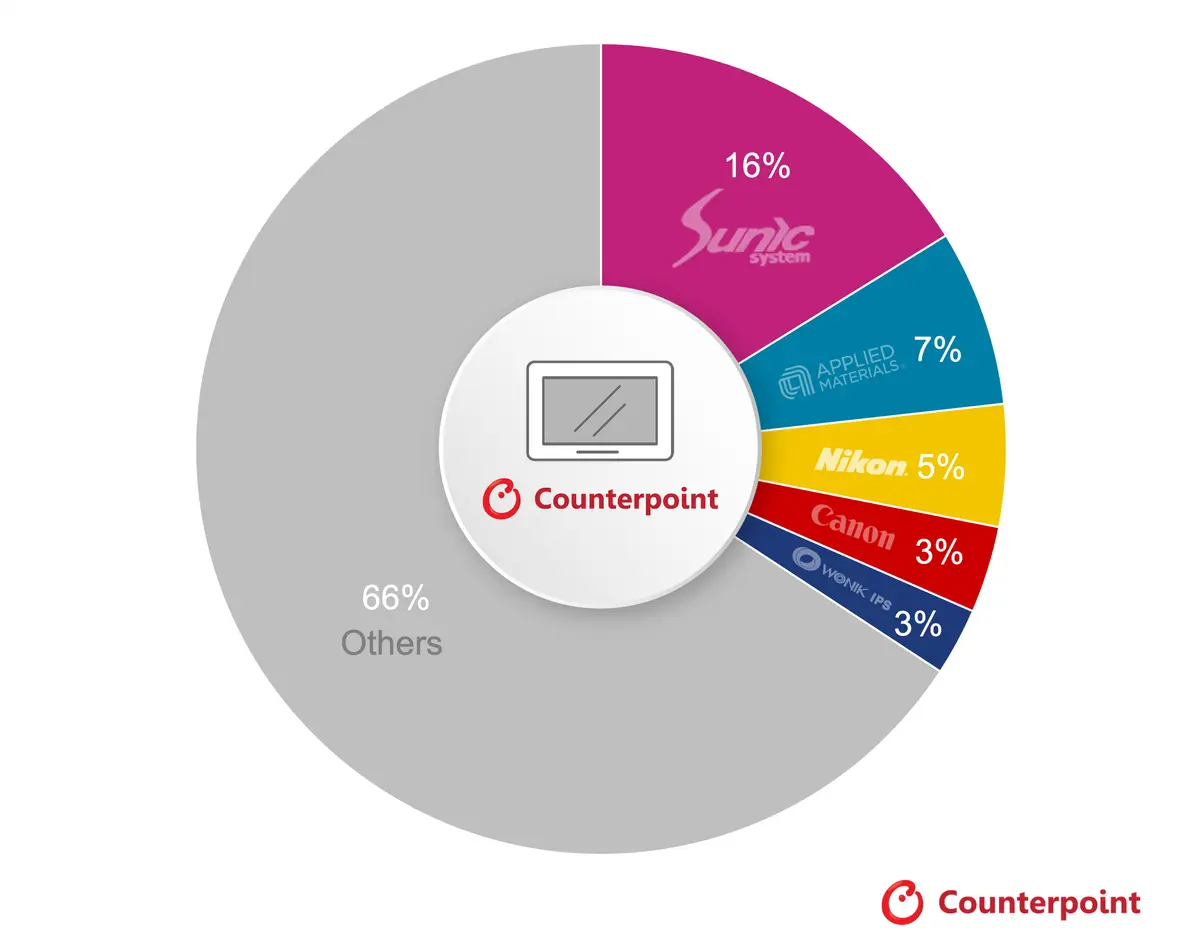
- Sunic System is forecast to become the first South Korean equipment maker to lead the display equipment market by revenue in 2027
- A roughly 3.5x YoY jump in DRAM prices in Q3 2026 is pushing smartphone OEMs to delay or scale back new display technology investments
- Samsung Display and LG Display are slowing or trimming planned Gen 6 smartphone display technology investments as a result
Beijing, Berlin, Buenos Aires, Fort Collins, Hong Kong, London, New Delhi, Seoul, Taipei, Tokyo – November 4, 2026
Global display equipment capital expenditure is expected to decline 49% year-on-year in 2027, according to Counterpoint Research’s Display Capex Report 2026 Q4, which will be released tomorrow. The pullback follows a 61% YoY surge in 2026, when investment was concentrated in 8.7-Gen IT OLED lines at BOE’s B16, Visionox’s V5 and China Star Optoelectronics Technology’s (CSOT) T8, alongside 8.6-Gen LCD investment at Tianma’s TM19. In 2027, spending on new technology development and supplementary investment will continue, but the absence of another large-scale project on the scale of BOE’s B16 Phase 2 is expected to pull total capex down sharply.
Display Capex Revenue 2025 vs 2026 vs 2027
Source: Counterpoint Research Display Capex Report 2026 Q4
DRAM prices rose roughly 3.5x year-on-year in the third quarter of 2026, significantly raising cost pressure on smartphone makers. That pressure is reshaping the timing of new display technology adoption. Premium flagship models such as the Galaxy Z Fold8 and iPhone Duo have been able to absorb some of the added cost through premium pricing and differentiated features despite adopting new display technologies. Mainstream bar-type smartphones, however, have already seen retail prices rise by at least $100 in the U.S., leaving little room to pass on further cost increases. As a result, Samsung Display and LG Display are delaying or scaling back planned investments in new Gen 6 smartphone display technology.
“Following the peak of $15.8 billion in 2020, the highest level of display investment in the past decade, 2026 capex of $10.8 billion represents about 68% of that peak,” said Jayden Lee, Associate Director at Counterpoint Research. “That is still modest compared with semiconductor investment driven by AI data center expansion, but the ramp-up of 8-Gen IT OLED investment has raised expectations of a rebound for the display industry. Samsung Display, in particular, plans to mass-produce OLED panels for Apple’s MacBook Pro at its 8-Gen IT OLED fab and launch the product within the year. Even so, rising memory prices are becoming a headwind for new display technology adoption and related capital spending, and we expect 2027 investment to fall 49% from 2026.”
Sunic System is projected to become the first South Korean equipment maker to top the display equipment market by revenue in 2027. The company has won the full order for the fine metal mask (FMM) deposition equipment essential to OLED pixel formation at BOE’s B16 fab, and has also been building strength in silicon wafer-based Micro-OLED (OLEDoS) deposition equipment for high-resolution VR applications. While Canon Tokki has historically dominated the OLED deposition equipment market, Sunic System has been gaining ground and expanding its footprint since the start of 8-Gen IT OLED investment. Samsung Display is expected to pursue the industry’s first 12-inch wafer-based RGB Micro-OLED investment, and Sunic System is seen as a strong candidate to be selected as the deposition equipment maker for that project. Separately, and not reflected in this report, Sunic System is also expanding into 8-Gen-class perovskite equipment for solar cells, broadening its specialized equipment portfolio as a foundation for mid- to long-term growth.
Top 5 Display Equipment Supplier by Revenue 2027
Source: Counterpoint Research Display Capex Report 2026 Q4
About Counterpoint Research
Counterpoint Research is a global market research firm specializing in products across the technology ecosystem. We advise a diverse range of clients – from smartphone OEMs to chipmakers and channel players to Big Tech – through our offices located in the world's major innovation hubs, manufacturing clusters and commercial centers. Our analyst team, led by seasoned experts, engages with stakeholders across the enterprise – from the C-suite to professionals in strategy, analyst relations (AR), market intelligence (MI), business intelligence (BI), product and marketing – to deliver services spanning market data, industry thought leadership and consulting. Our core areas of coverage include AI, Automotive, Consumer Electronics, Displays, eSIM, IoT, Location Platforms, Macroeconomics, Manufacturing, Networks and Infrastructure, Semiconductors, Smartphones and Wearables. Visit our Insights page to explore our publicly available market data, insights and thought leadership, and to understand our focus, meet our analysts and start a conversation.
Follow Counterpoint Research